
Getting a self-employed mortgage UK is not harder than getting one as an employee. It is just different, and the difference sits almost entirely in one place: how your income is calculated. While a salaried applicant hands over three payslips and moves on, a self-employed borrower faces a maze of business structures, averaging methods, tax optimisation trade-offs, and lender policies that vary more than most advisors will tell you upfront. If you have been told your income “looks complicated,” the real problem is usually that you are talking to the wrong lender, or you walked in without understanding how your income will be read. This guide explains exactly how lenders assess what you earn, what they want to see, and where most self-employed applications go wrong.
Table of Contents
- Quick Takeaways
- What “Self-Employed” Actually Means to a Lender
- How Lenders Assess Income by Business Type
- The Documents Every Lender Will Ask For
- How Many Years of Accounts Do You Need?
- The Tax Efficiency Trap
- CIS Contractors: A Different Assessment Entirely
- Income Averaging Methods Compared
- How Much Can You Borrow?
- How to Strengthen Your Application Before You Apply
- Frequently Asked Questions
- References
Quick Takeaways
| Key Insight | Explanation |
|---|---|
| Two years of accounts is the standard minimum | Most high-street lenders require at least two years of SA302s or certified accounts. A growing number of specialist lenders will accept one year, with conditions. |
| Lenders average your income, not just the latest year | If your profits fluctuate, most lenders take a two-year average. A single dip year will reduce what you can borrow, even if the most recent year was strong. |
| Tax efficiency works against you at application time | Aggressive expense claims and low salary drawings reduce declared profit, which directly cuts your borrowing capacity at a 4 to 4.5x income multiple. |
| Limited company directors are not assessed on turnover | Most lenders count only the salary and dividends you actually drew. Retained profit in the company is typically ignored unless you use a specialist lender. |
| CIS contractors have a specialist assessment route | Lenders who understand CIS payslips annualise your gross contract income rather than treating you as a standard self-employed applicant, which significantly improves borrowing power. |
| SA302 and Tax Year Overview must be submitted together | Submitting an SA302 without the matching Tax Year Overview will cause the majority of lenders to reject the documentation outright. |
| Lender selection matters more than product rate | The variable that moves your borrowing most is not the interest rate. It is which lender you choose and how they define your assessable income. |
What “Self-Employed” Actually Means to a Lender
Most mainstream lenders classify a borrower as self-employed if they own more than 25% of a business. That threshold catches sole traders, freelancers, business partners, and limited company directors with a meaningful ownership stake. Once you cross it, the lender’s underwriting team cannot rely on a payslip to verify what you earn. They have to reconstruct your income from tax records, and that is where the complexity starts.
There is no such thing as a dedicated “self-employed mortgage” product in the UK. Self-employed applicants access the same residential and buy-to-let mortgage deals as employed borrowers. The product range available to you is identical. What changes entirely is how your income is verified and what figure the lender uses to calculate how much they will lend.
The practical consequence is that two self-employed borrowers with identical actual earnings can receive very different offers depending on their business structure and which lender they approach. Sole traders, limited company directors, and CIS subcontractors are all assessed differently, and the gap between the best and worst lender decision for any one applicant can run to tens of thousands of pounds in borrowing capacity.
How Lenders Assess Income by Business Type
This is the section that actually determines your mortgage outcome. Every other part of the process is standard. How your income is defined is not.
Sole Traders
If you are a sole trader, lenders assess you on your net profit as declared on your Self Assessment return, evidenced by SA302 tax calculations. That means the figure after all allowable business expenses have been deducted. Most lenders average the last two years of net profit. Some will use the most recent year only if income is clearly trending upward, which can make a meaningful difference when your business is growing fast.
If the most recent year is lower than the prior year, however, most lenders apply the lower figure rather than the average. This is a point that catches a lot of sole traders off guard, particularly those who had a quiet year due to illness, a contract gap, or planned investment in the business.
Limited Company Directors
The standard assessment for a limited company director is salary plus dividends drawn. The lender adds your PAYE salary to the dividends you actually extracted from the company and treats the total as your annual income. For directors who draw a low salary for tax efficiency purposes and modest dividends, the assessed income can be surprisingly low relative to the company’s actual performance.
A smaller group of lenders will instead assess salary plus your share of the company’s net profit, which is the more generous calculation for directors who retain earnings. A few specialist lenders go further and include retained profit in proportion to your shareholding. The difference between these approaches can be substantial. If you have been advised to minimise your drawings for tax purposes, it is worth working with an advisor who knows which lenders take the net profit route before you apply.
Freelancers and Contractors (Outside CIS)
For contractors outside of the Construction Industry Scheme, the assessment generally follows either the sole trader or limited company route depending on how the contractor is structured. Some lenders who specialise in contractor mortgages will annualise the day rate, typically using a formula of day rate multiplied by five days multiplied by 46 to 48 weeks. This method is more generous than averaging historic accounts for contractors with strong current contracts, particularly when they are new to self-employment.
The Documents Every Lender Will Ask For
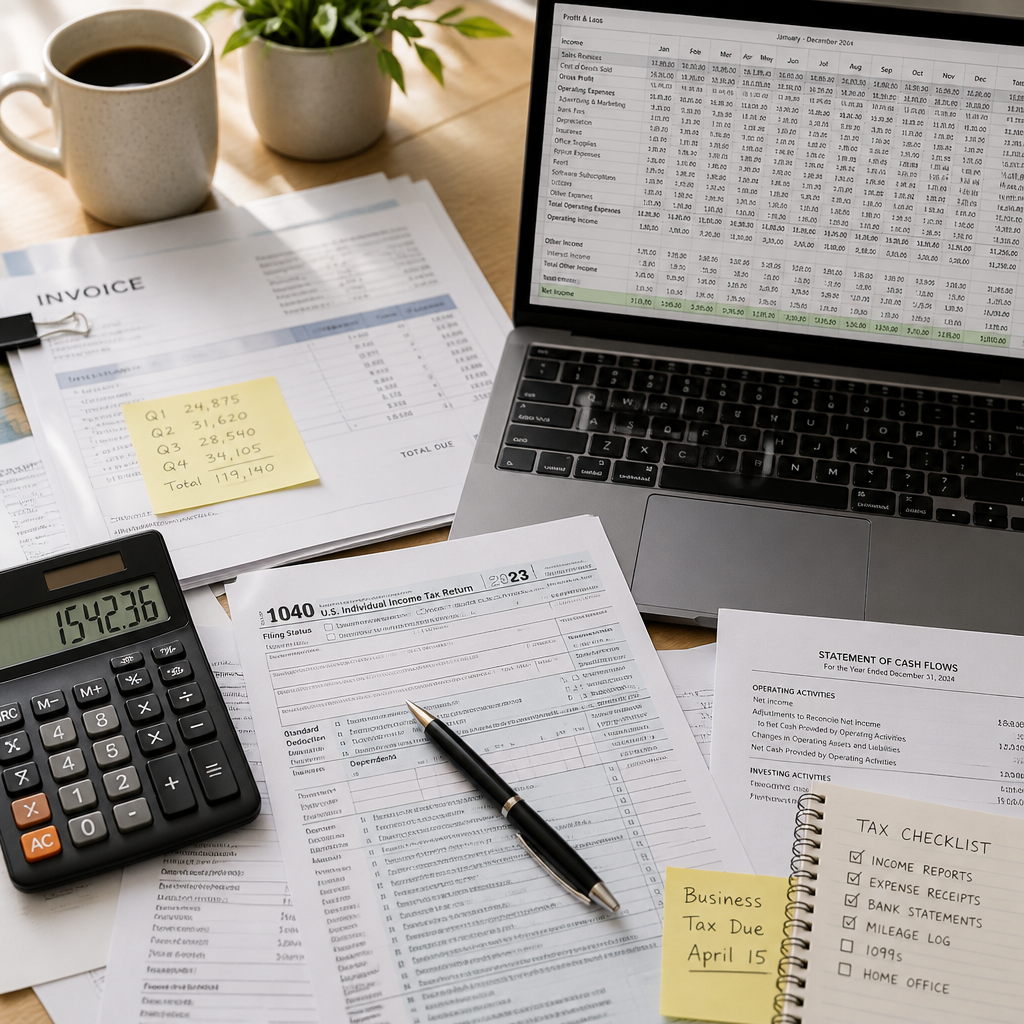
Documentation requirements are fairly consistent across lenders, although the number of years they want varies. For a standard self-employed mortgage application, you will need SA302 tax calculations from HMRC covering the last two to three tax years, the matching Tax Year Overviews for each year (the pairing is mandatory and most lenders will reject an SA302 submitted without its corresponding overview), and three to six months of business and personal bank statements.
Limited company directors will also need their last two years of company accounts, usually prepared and certified by a qualified accountant. Some lenders require an accountant’s certificate or reference letter confirming the business is trading, the accounts are accurate, and the income is expected to continue. If you file your own accounts without an accountant, be aware that a small number of lenders require accounts prepared by a chartered or certified accountant, not just any qualified professional.
Pro tip: Request your SA302s directly from HMRC Online Services rather than asking your accountant to generate a tax computation. HMRC-issued SA302s are universally accepted. Accountant-generated tax computations are accepted by most lenders but not all, and they must always be submitted alongside the HMRC Tax Year Overview.
Beyond the income documents, standard mortgage application requirements apply: photo ID, proof of address, details of existing credit commitments, and, for a purchase, the property details and confirmation of your deposit source.
How Many Years of Accounts Do You Need?
Two years is the working standard for high-street lenders. That means two full tax years of self-employed income evidenced by SA302s and Tax Year Overviews. Some lenders ask for three years, which produces a more conservative income average and can dilute the effect of a particularly strong recent year.
One year of accounts is possible with specialist lenders, but it comes with conditions. Lenders considering a one-year application typically want to see a strong credit history, a larger deposit, a healthy income level, previous experience in the same industry or profession before going self-employed, and some evidence of future work or contracts. The FCA has also been consulting on reforms to help self-employed borrowers, with broader changes to affordability assessments expected in 2026.
At Albion Forest, we work with lenders across the full spectrum. If you have only one year of accounts, that does not automatically rule you out. What it does is reduce the lender panel and usually increase the importance of how your application is packaged and presented.
The Tax Efficiency Trap
This is the most common and most expensive mistake self-employed mortgage applicants make, and it is entirely preventable with planning.
When you claim allowable business expenses, you reduce your taxable profit, which reduces your tax bill. That is entirely legitimate and smart business practice. The problem is that lenders assess your income from the same declared profit figure. Every pound of expenses you claim reduces the income a lender will count, and at a borrowing multiple of 4 to 4.5 times income, every reduction in declared profit has a multiplied effect on how much you can borrow.
The tension between tax efficiency and mortgage affordability is real and unavoidable. The year you plan to buy should not be the year you claim every optional expense available to you. Decide which priority matters most before that tax return is filed.
For limited company directors, the same logic applies to retained profit. The tax-efficient strategy of leaving profit in the company and drawing a low salary works against you when the lender’s assessment is based purely on your personal drawings. If you are planning to apply for a mortgage in the next one to two years, talk to both your accountant and a specialist mortgage advisor before deciding on your salary and dividend strategy. Changing course after the tax return is filed is not possible. Changing course before it is filed, with the mortgage application in mind, absolutely is.
Pro tip: Some self-employed borrowers preparing to apply for a mortgage adjust their income strategy for one to two years in advance, reducing optional expense claims and increasing drawings to raise their declared income. Whether this is right for you depends on your personal tax position, so take accountancy advice alongside mortgage advice. What matters is that you make the decision consciously, not by accident.
CIS Contractors: A Different Assessment Entirely
Construction Industry Scheme contractors occupy a distinct position in the self-employed mortgage market. Most CIS subcontractors are registered as self-employed, but lenders who understand the scheme assess CIS income differently from a standard sole trader, and the distinction significantly affects borrowing capacity.
Rather than averaging two or three years of net profit from SA302 returns, lenders who specialise in CIS mortgages use gross CIS payslips to calculate income. The most common method is to take the last three months of CIS payslips, calculate a monthly average, and annualise that figure. Some lenders annualise over 46 weeks to allow for holidays and downtime, others use a full 52-week year. The calculation method used makes a material difference to the assessable income figure.
For a CIS contractor earning a consistent weekly gross income, the payslip-based route typically produces a far higher assessable income than a two-year SA302 average would, because SA302 figures reflect net profit after any allowable deductions. This is why many CIS subcontractors who have been declined or offered very low amounts by standard lenders do significantly better when their application is directed to a lender that understands the CIS framework. At Albion Forest, CIS mortgage applications are one of our specialist areas precisely for this reason.
Income Averaging Methods Compared
Not all lenders use the same averaging method, and the choice of averaging approach can significantly change your assessed income. The table below sets out the three main approaches used across the UK lender market.
| Averaging Method | How It Works | Best For |
|---|---|---|
| Two-year average (most common) | Lender adds Year 1 and Year 2 net profit (or salary plus dividends) and divides by two. If the most recent year is lower, many lenders use the lower figure instead of the average. | Borrowers with stable or slowly growing income. Works against applicants with a single bad year. |
| Latest year only | Lender uses only the most recent tax year’s income figure. Available from a smaller number of lenders, often requiring stronger overall profile. | Borrowers with sharply rising income where the latest year is substantially higher than the prior period. |
| Three-year average (most conservative) | Lender averages income across the last three tax years. Dilutes the effect of one strong year but also softens the impact of one weak year. | Borrowers with consistent income over three years where a single recent dip does not reflect the longer trend. |
The right lender for you depends on your specific income pattern. A borrower whose most recent year was their strongest ever should be targeting lenders who will use the latest year only. A borrower with a single quiet year two years ago should be targeting lenders who average three years rather than those who apply the lower-of-two rule. This is not guesswork. A specialist broker maps your income profile to the lender methodology before you apply.
How Much Can You Borrow?
The income multiples applied to self-employed borrowers are the same as those for employed borrowers. Mainstream lenders typically offer between four and four and a half times your assessed annual income, with some lenders stretching to five or five and a half times in the right circumstances, particularly for higher earners or professional borrowers.
The variable that changes your borrowing most is not the multiple. It is how the lender defines your income in the first place. Two lenders offering the same 4.5x multiple will produce very different loan offers if one assesses a limited company director on salary plus dividends while the other assesses on salary plus net profit. The assessed income figure is the lever, and that is where the expertise of an advisor who knows the specific lender policies pays off most directly.
Your deposit size also matters beyond just meeting the minimum loan-to-value requirement. A larger deposit increases your access to more lenders, including those who would otherwise decline on grounds of income complexity, and reduces the rate you pay. If you are approaching an application with one year of accounts or a fluctuating income history, a stronger deposit position can meaningfully widen your options.
How to Strengthen Your Application Before You Apply
The best time to prepare a self-employed mortgage application is twelve to eighteen months before you intend to apply. That window gives you time to adjust your income strategy, tidy up your credit file, and ensure your accounts are in order. Arriving at a lender without preparation and expecting them to accommodate a complex income profile rarely ends well.
Check your credit report across all three main credit reference agencies used in the UK. Errors on credit files are more common than most people expect, and they are straightforward to correct once identified. Missed payments, outdated records, and unregistered addresses all affect your credit score and are fixable with lead time. Avoid making multiple credit applications in the period leading up to your mortgage application, as each one leaves a footprint that can raise questions for underwriters.
File your Self Assessment returns on time, every time. A late filing, even by a few days, can appear on your record and is the kind of flag that a cautious underwriter will ask about. If you are applying after 6 April, you can file the new tax year’s return immediately. Some lenders will accept the most recent tax year’s figures as soon as they are filed, which can update your income picture materially if the latest year was your strongest.
Finally, use an advisor who has direct access to the full lender market and who specialises in self-employed cases. Self-employed mortgages are not declined because the applicant cannot afford the mortgage. They are declined because the application was sent to the wrong lender, or because the income documentation was not packaged in the way that lender’s underwriters expected to see it. Getting this right at the first attempt matters. A declined application leaves a footprint, and that footprint can complicate the next application.
Frequently Asked Questions
Can I get a self-employed mortgage with one year of accounts?
Yes, it is possible. A growing number of specialist lenders will consider applications with just twelve months of trading history. To access these lenders you will typically need a strong credit history, a healthy deposit, consistent income through the first year, and preferably previous experience in the same industry before going self-employed. Your options are more limited than with two years of accounts, but the route is there with the right broker and the right lender.
How does a lender calculate income for a limited company director?
Most lenders assess a limited company director on salary plus dividends drawn during the year. A smaller but important group of lenders will instead use salary plus the director’s share of the company’s net profit, which is significantly better for directors who retain earnings in the business. Knowing which lenders take the net profit approach is one of the most valuable things a specialist advisor brings to this type of application.
Does being self-employed affect the mortgage rate I receive?
No. There is no self-employed premium on mortgage interest rates in the UK. Self-employed borrowers access exactly the same product range and the same rates as employed borrowers. What differs is the income documentation required and how that income is assessed. The rate you receive depends on your loan-to-value ratio, credit profile, and the lender, not your employment status.
What is the difference between an SA302 and a Tax Year Overview?
The SA302 is a tax calculation document that shows a full breakdown of your income, allowances, and the tax owed for a given year. The Tax Year Overview is a shorter summary document from HMRC confirming that your Self Assessment tax has been paid. Lenders require both documents together. Most will reject an SA302 submitted without the matching Tax Year Overview. Both are available to download from your HMRC online account, typically at least 72 hours after you submit your Self Assessment return.
Why would a self-employed mortgage application be declined?
The most common reasons are: a declining income trend over the assessed years, declared profit that has been reduced heavily by expense claims, a recent late tax filing, unexplained items on the credit file, and applying to a lender whose criteria simply do not suit the applicant’s business structure. Most of these issues are preventable with planning or solvable by choosing a more suitable lender. A declined application at one lender does not mean the mortgage is unavailable. It usually means the application needs to be repositioned.
Do CIS contractors need to submit SA302s for a mortgage?
Not necessarily. Lenders who specialise in CIS mortgages assess income using gross CIS payslips rather than SA302 tax returns. This is usually far more advantageous for CIS subcontractors because the gross payslip figure is higher than the net profit declared on a Self Assessment return. The key is ensuring your application goes to a lender who accepts and understands CIS payslip-based income. A standard self-employed route would typically undersell a CIS contractor’s true earning capacity.
If you are self-employed and navigating the mortgage process, we would love to hear what part of the income assessment has been most confusing or surprising for you. Leave a comment or get in touch directly.
References
- Heron Financial: How lenders assess self-employed income by business structure
- UBMFS: Getting a mortgage when self-employed in the UK, 2026 guide
- Xero UK: What is an SA302 form and how to obtain it from HMRC
- Strive Mortgages: How lenders calculate CIS contractor income for mortgage applications
- Mortgage Affordability: How UK lenders calculate self-employed mortgage affordability