
Most people searching for mortgage affordability UK information expect one tidy number. What they get instead is confusion: a lender telling them they can borrow £350,000, an online calculator spitting out £280,000, and a friend swearing they borrowed six times their salary. All three can be true at once, because mortgage affordability in the UK is not a single calculation. It is a layered system involving income multiples, stress tests, committed expenditure checks, and lender-by-lender policy differences. If you do not understand the layers, you will either aim too low and miss a property you could genuinely afford, or aim too high and face a rejection that damages your credit file.
Table of Contents
- Quick Takeaways
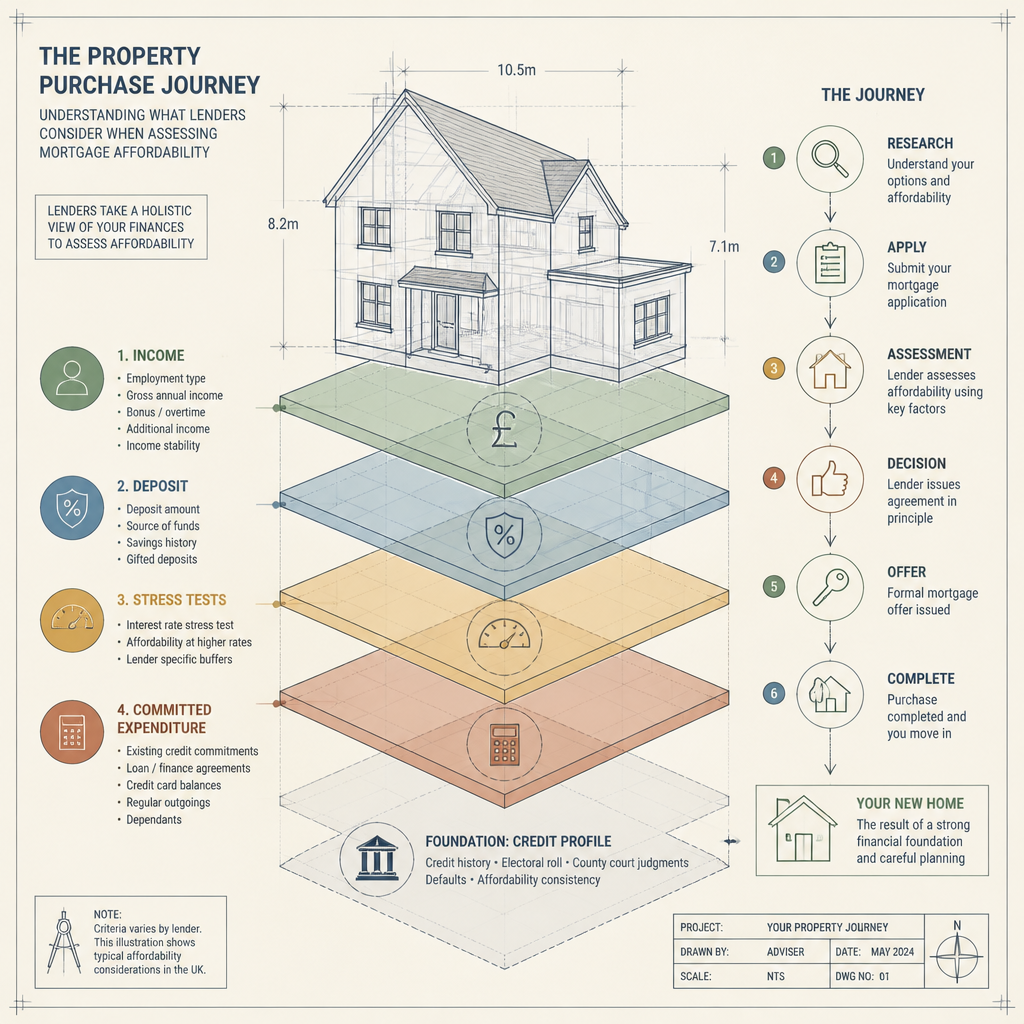
- The Three Layers of UK Mortgage Affordability
- Income Multiples Explained: 4.5x Is Not the Ceiling
- What Actually Reduces How Much You Can Borrow
- Self-Employed and CIS Contractors: How Lenders Calculate Your Income
- How Deposit Size Changes the Picture
- Comparing Your Options: Standard, Enhanced, and Specialist Lending
- Common Mistakes That Cut Your Borrowing Power
- Frequently Asked Questions
- References
Quick Takeaways
| Key Insight | Explanation |
|---|---|
| 4.5x is the default, not the maximum | Standard high street lenders offer 4.0x to 4.5x income, but several major lenders now go to 5.5x, and some specialist routes reach 6.0x to 6.5x for eligible borrowers. |
| Your debts shrink your borrowing more than most people realise | Every £100 per month in existing committed debt can reduce your total borrowing power by thousands of pounds. Lenders convert monthly commitments to an annual figure and deduct it before applying any multiple. |
| The stress test is where many applications fail silently | Lenders test your ability to repay at a rate typically 1% to 2% above the product rate. If you cannot pass that test on paper, the income multiple is irrelevant. |
| Self-employed and CIS borrowers need lender-matching, not just a calculator | How lenders calculate self-employed income varies enormously. The same accounts can produce a borrowable figure that differs by tens of thousands of pounds depending on which lender reviews them. |
| A larger deposit unlocks higher multiples and better rates | Crossing from 90% LTV to 85% LTV or below often changes both the rate you are offered and the income multiple available to you. |
| The LTI flow limit affects lender behaviour, not just individual applications | The Bank of England restricts lenders’ aggregate high-LTI lending. Reforms proposed in 2026 would give individual lenders more flexibility, potentially making higher multiples more accessible. |
| Online calculators give an envelope, not an answer | Affordability calculators are useful for orientation but cannot replicate a lender’s full assessment. An adviser who knows which lender will treat your income most favourably is worth more than any calculator output. |
The Three Layers of UK Mortgage Affordability
Understanding mortgage affordability UK starts by recognising that three separate bodies shape what you can borrow, and each operates independently. If you only focus on income multiples, you are looking at one layer of a three-layer system.
The first layer is the Bank of England’s Financial Policy Committee, which sets macroprudential limits. The most relevant is the loan-to-income flow limit: a rule that restricts the proportion of mortgages any lender can issue at an LTI ratio of 4.5 or above to 15% of their total new residential mortgage lending. In 2026, the Bank of England and FCA are consulting on proposals to remove the 15% LTI flow limit for individual firms while keeping aggregate lending consistent with that limit, which would give lenders more flexibility to offer higher multiples without hitting an internal policy ceiling.
The second layer is the FCA’s conduct rules under MCOB 11.6. These require lenders to verify income, assess committed expenditure, and apply a forward-looking interest rate stress test. The FCA reminded lenders in March 2025 that they had flexibility in how they applied their stress tests, and several lenders responded by widening their criteria.
The third layer is each lender’s own internal risk model. This produces the income multiple, the stress margin, and the expenditure benchmarks that determine your actual offer. Two lenders applying the same regulatory rules can produce figures that differ by £40,000 or more on the same application.
Income Multiples Explained: 4.5x Is Not the Ceiling
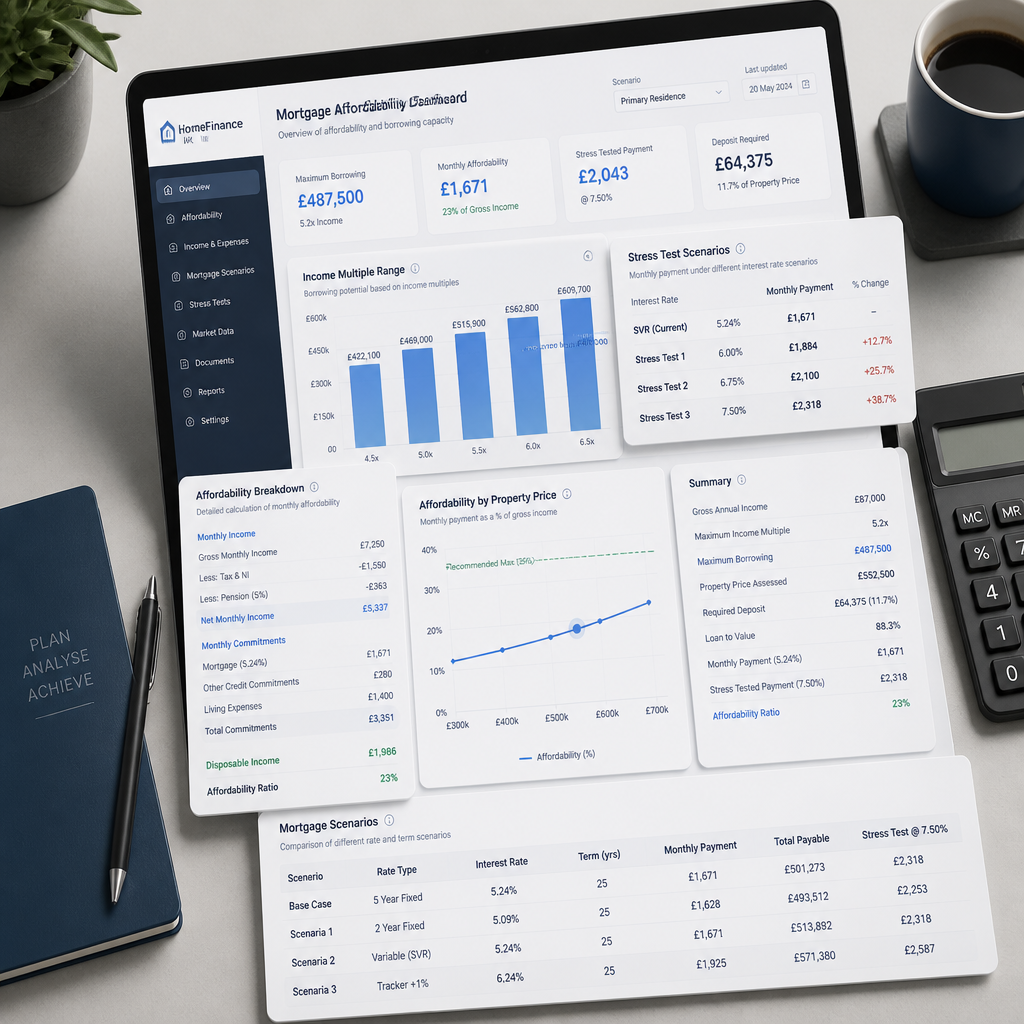
“Four and a half times your salary” is the figure most people carry into their first mortgage conversation. It is a starting point for a standard high street application, not a hard ceiling on what any lender in the UK will offer.
The 2026 income multiple landscape
In 2026, UK mortgage income multiples sit in four broad bands. The standard high street range of 4.0x to 4.5x applies to most employed applicants at mainstream lenders including Halifax’s standard range, Santander, NatWest standard tier, Barclays, and Nationwide. An enhanced tier of 5.0x to 5.5x is available at several of those same lenders for applicants earning above approximately £75,000, with a lower LTV and a strong affordability profile. Professional and first-time buyer schemes take some applicants to 6.0x. NatWest has moved to 6.5x for joint applications with combined income above £150,000, on a repayment basis and capped at 85% LTV.
The practical takeaway is that if your household income is £80,000 and you have assumed you can borrow no more than £360,000, you may in fact qualify for £400,000 to £440,000 under the right lender and product. That gap is large enough to change what property you can realistically buy.
The role of the stress test in limiting the multiple
Even where a lender’s policy allows 5.5x, the stress test can overrule it. Lenders check whether you could still afford the monthly repayments if the interest rate were to rise, typically testing at 1% to 2% above the product rate. If your monthly payment at the stress rate would exceed their affordability threshold given your income and outgoings, the maximum multiple on paper is irrelevant. You simply cannot borrow that much from that lender.
The income multiple is the ceiling, but the stress test is the door. A high ceiling is no use if you cannot get through the door.
Pro tip: If you are renewing or stress-testing your affordability before a purchase, ask an adviser to run the stress test calculation, not just the income multiple. It is the more likely constraint for borrowers seeking higher multiples.
What Actually Reduces How Much You Can Borrow
Most people focus on what they earn. Lenders focus equally hard on what you owe and spend. These are the factors that routinely surprise applicants who thought their income was strong enough.
Committed debt: the silent reduction
Lenders convert all your monthly committed debt payments, including car finance, personal loans, student loan repayments, and credit card minimum payments, into an annual figure. They then subtract that from your gross income before applying the income multiple. If you have £400 per month in existing commitments, that is £4,800 per year. At a 4.5x multiple, that single figure reduces your borrowing capacity by approximately £21,600. At higher income levels, the reduction scales accordingly.
A common mistake is to assume that because a debt is nearly paid off, it will be ignored. Most lenders count a commitment even if it ends in three to six months’ time. Clearing it before you apply, where you have that option, is nearly always worth doing.
Childcare costs and household expenditure
Since the 2014 Mortgage Market Review, lenders have been required to assess committed expenditure, not just income. This includes regular childcare costs. Applicants with young children can find their assessed affordability is materially lower than a raw income multiple would suggest, simply because the lender has factored in the ongoing cost of nursery or wraparound care.
Number of dependants
Each declared dependant reduces the income available for mortgage servicing in a lender’s model. This is not a reason to be less than honest on an application. It is a reason to seek out lenders whose expenditure benchmarks treat dependants more generously, and a good broker will know which lenders those are.
Pro tip: Before applying, pull together your last three months of bank statements and add up every regular committed outgoing. This is exactly what a lender will do. If the figure surprises you, it will not surprise you on the day of the application.
Self-Employed and CIS Contractors: How Lenders Calculate Your Income
For employed borrowers, income assessment is relatively straightforward. For self-employed borrowers, and especially for CIS contractors, the same income can generate radically different borrowing figures depending on which lender reviews the application and how they treat each income type.
Sole traders and limited company directors
If you are a sole trader, lenders assess your income as net profit. They verify this through your SA302 tax calculations and tax year overviews from HMRC. Most lenders use the average of the last two tax years. Some use the most recent year only, which helps where income has been growing. A few use a three-year average, which can significantly dilute the impact of a strong recent year. The variation between lenders on this single point can change your assessed income by tens of thousands of pounds.
Limited company directors face an additional variable. Some lenders use salary plus dividends taken. Others use salary plus the company’s share of net profit, regardless of whether it was drawn. The second approach can dramatically increase the income a director is assessed on, but not every lender offers it.
CIS contractors: a different calculation entirely
CIS (Construction Industry Scheme) contractors occupy a specific position in UK mortgage affordability. Most lenders treat them as self-employed, requiring two years of SA302s, and then assess income using the self-employed methodology above. However, a CIS mortgage offered through specialist lenders takes a different approach: these lenders annualise the contractor’s gross CIS earnings rather than relying on net profit declared through Self Assessment. Because CIS subcontractors often show modest declared profit after expenses, the CIS-specific approach can produce a significantly higher assessed income and therefore a higher borrowing limit.
The difference between a standard self-employed application and a properly structured CIS mortgage application on the same income can easily exceed £50,000 in borrowing power. Choosing the wrong lender type is not a minor inefficiency here. It is a substantive financial decision.
Day-rate contractors
For contractors operating on a daily rate, some lenders annualise the current day rate, typically calculated as day rate multiplied by five days multiplied by approximately 46 working weeks. That annualised figure is then treated like an employed salary for the purposes of the income multiple. Lenders using this approach usually require the contract to have at least four to six weeks remaining at the point of application.
How Deposit Size Changes the Picture
Deposit size affects mortgage affordability UK in two distinct ways. The first is obvious: a larger deposit means a smaller loan, so you are borrowing less against the same property. The second is less obvious but often more significant for the income multiple you can access.
Lenders treat loan-to-value (LTV) as a risk indicator, and many of their enhanced income multiple tiers are gated behind LTV thresholds. A borrower at 90% LTV may be capped at 4.5x, while the same borrower at 80% LTV qualifies for 5.0x or even 5.5x at the same lender. If you are close to a threshold, stretching the deposit slightly to cross it can increase both the rate you are offered and the multiple available to you.
The minimum deposit most lenders require is 5% of the property value, though 10% is more common in practice for mainstream products. Reaching 15% or above significantly broadens your product range. The improvement in available multiples often accelerates again at 25% deposit, which is the point where many lenders consider LTV risk to be low enough to apply their most generous criteria.
Comparing Your Options: Standard, Enhanced, and Specialist Lending
When thinking about mortgage affordability UK, the choice between lender tiers matters as much as your income level. Below is a comparison of the three main routes available to UK borrowers in 2026.
| Lending Route | Typical Income Multiple | Best Suited For |
|---|---|---|
| Standard high street lending (Halifax, Nationwide, Barclays, Santander standard tiers) | 4.0x to 4.5x single income; 3.5x to 4.0x joint income | Employed applicants with straightforward income, standard credit profiles, and LTV above 85% |
| Enhanced / professional scheme lending (NatWest higher income tier, Halifax enhanced, first-time buyer boost products) | 5.0x to 6.5x depending on income level and LTV | Higher earners (typically £75,000+), professionals, joint applicants with £150,000+ combined income, first-time buyers on qualifying products |
| Specialist lending (CIS mortgage lenders, specialist self-employed lenders, contractor-specific products) | 4.0x to 5.5x but based on gross CIS earnings or annualised day rate rather than declared profit | Self-employed borrowers, CIS subcontractors, limited company directors with significant retained profit, and applicants whose declared income understates actual earning power |
The key insight from this comparison is that the same borrower will often achieve a materially different result from each route. A CIS contractor earning £60,000 gross may find that a standard self-employed application based on declared net profit produces a borrowing limit of £180,000, while a correctly structured CIS mortgage from a specialist lender produces £240,000 or more. The route you take matters, and the route you are put on depends entirely on who advises you.
Common Mistakes That Cut Your Borrowing Power
Working through mortgage applications every week reveals a consistent set of errors that cost applicants borrowing capacity they were entitled to. These are not exotic edge cases. They are routine errors made by people who did not know what lenders were actually looking for.
Applying to the wrong lender type
For self-employed and CIS borrowers in particular, applying to a standard high street lender using standard self-employed assessment when a specialist CIS product exists is the single most costly mistake. It is not a matter of preference. It is a matter of which income figure the lender will assess, and that figure can differ enormously.
Allowing unnecessary credit commitments to remain open
Open credit card accounts with a zero balance are still counted in a lender’s affordability model if they represent available credit that could be drawn down. Some lenders factor available credit, not just actual debt, into their committed expenditure calculation. Closing dormant accounts before applying removes that exposure.
Not understanding what counts as income
Many lenders will accept a proportion of regular bonus, overtime, commission, rental income, and investment income alongside basic salary. Applicants who declare only their base salary and assume the rest will not count often leave significant borrowing headroom on the table. A broker who knows a lender’s income policy in detail can advise which income streams to include and how to evidence them.
Using online calculators as a definitive answer
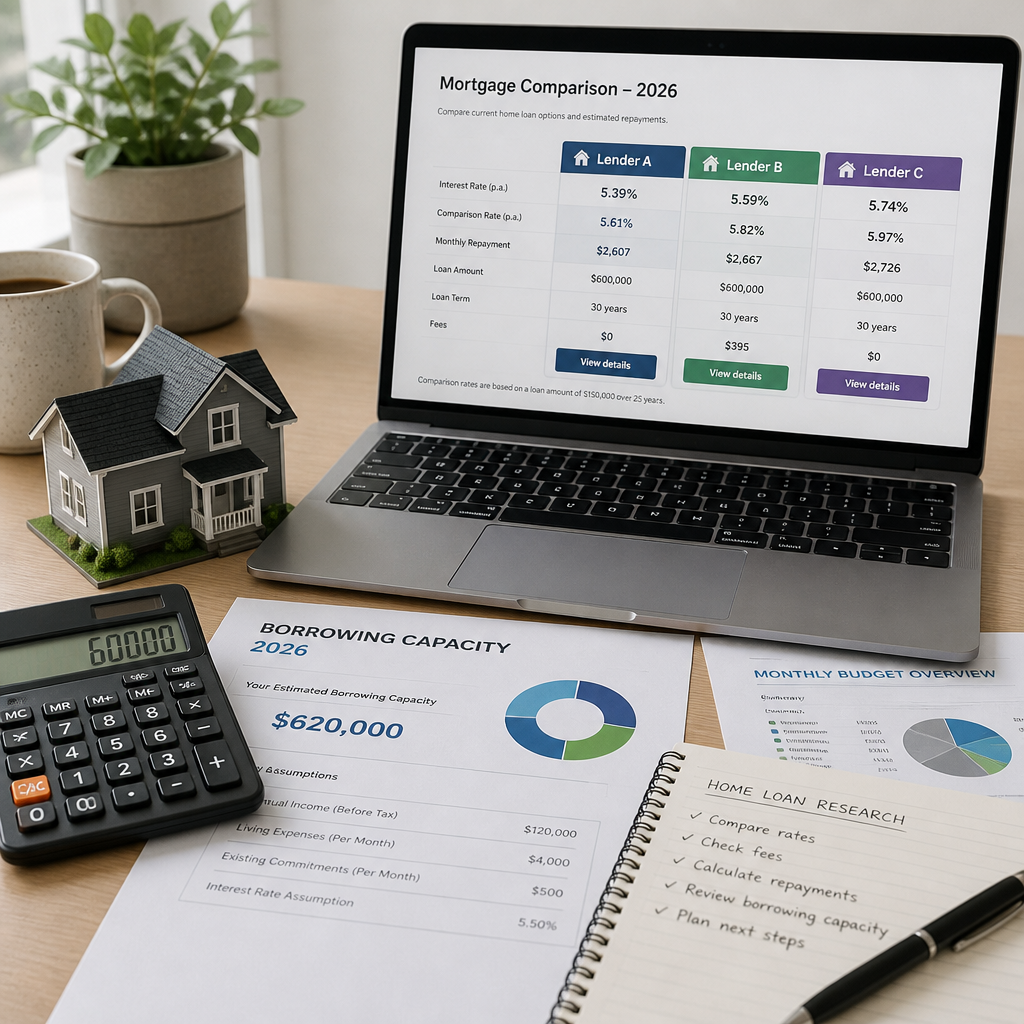
Online affordability calculators are useful tools for setting expectations and understanding the rough range of what you might borrow. They are not a substitute for a full lender assessment. A calculator cannot replicate the nuance of how a specific lender treats your specific income type, your specific debt profile, or your specific LTV. Treating a calculator output as a hard figure leads to either over-confidence or unnecessary pessimism, and neither serves you well in a property transaction.
At Albion Forest Mortgages, the approach is to run your income and commitments through the actual criteria of the lenders most likely to offer you the best outcome, not through a generic calculator. That lender-by-lender matching is what produces a realistic and maximised figure before you make an offer on a property.
Frequently Asked Questions
How much can I borrow on a mortgage in the UK in 2026?
Most UK borrowers can access between 4.0x and 4.5x their gross annual income through standard high street lenders. Higher earners with lower LTVs can access 5.0x to 5.5x through enhanced tiers, and some products reach 6.0x to 6.5x for qualifying applicants. The exact figure depends on your income type, your committed debts, your deposit size, and which lender you apply to. Self-employed borrowers and CIS contractors often find the right specialist lender delivers significantly more than a standard high street application would suggest.
What is the mortgage income multiple for a joint application?
For joint applications, standard high street lenders typically use 3.5x to 4.0x combined gross income, though this varies by lender. Some lenders apply the same multiple to joint income as to single income, while others use a tiered system where the multiple increases as combined income rises. NatWest’s 6.5x tier, for example, requires combined income above £150,000. If your joint income crosses a lender’s threshold for an enhanced multiple, it is worth mapping which specific lenders will treat that income most generously.
Does the stress test stop me from borrowing as much as the income multiple suggests?
Yes, it can. The stress test checks whether you could still afford the monthly repayments if the interest rate rose, usually by 1% to 2% above the product rate. If your monthly payment at the stress rate would be too high relative to your income and outgoings, the lender will cap your borrowing below the income multiple ceiling. The stress test is particularly relevant at higher income multiples, where the monthly payment is already substantial, and for borrowers with significant committed expenditure.
How do lenders assess income for CIS contractors?
Most standard lenders treat CIS subcontractors as self-employed, requiring two or more years of SA302 tax calculations and assessing income based on declared net profit. Specialist CIS mortgage lenders take a different approach, using gross CIS earnings from payslips or CIS vouchers and annualising them instead of relying on net profit. Because many CIS contractors have relatively low declared profit after legitimate business expenses, the specialist approach typically produces a higher assessed income and a larger mortgage offer. The difference can be substantial, so the choice of lender matters more than for most borrower types.
Will paying off debts before applying genuinely increase how much I can borrow?
Usually yes. Lenders convert monthly debt commitments to an annual figure and reduce the income available for mortgage servicing accordingly. Paying down a car finance agreement or personal loan before applying removes that drag from the affordability calculation. The impact depends on the size of the commitment, but even a relatively modest monthly payment can reduce borrowing capacity by a meaningful amount when multiplied by the income multiple. An adviser can calculate the exact borrowing improvement you would gain by clearing a specific debt, which helps you decide whether it is worth doing.
Does my credit score affect how much I can borrow on a mortgage?
Your credit score affects both whether you are approved and which lenders will consider you. Some lenders offer higher income multiples or better rates to borrowers with cleaner credit histories, which indirectly affects the maximum you can borrow. A poor credit history may restrict you to specialist lenders who offer lower multiples or require larger deposits, reducing your effective borrowing ceiling. Checking your credit report before applying and addressing any errors or outdated negative marks is a straightforward step that takes time but can materially affect your options.
How does Albion Forest Mortgages help maximise mortgage affordability?
Albion Forest Mortgages maps your income, including income types that standard calculators often miss, against the actual lending criteria of lenders likely to offer you the best outcome. For self-employed and CIS clients this means identifying which income assessment method produces the highest figure. For first-time buyers and key workers it means identifying enhanced multiple tiers and government-backed products you might not find through a direct bank approach. The result is a realistic, maximised borrowing figure before you start making offers, rather than a surprise restriction mid-application.
If you have had a different experience with mortgage affordability calculations or lender assessments, we would genuinely like to hear about it. Leave a comment below or get in touch directly.
References
- UK mortgage affordability rules in 2026: income multiples, stress tests, and LTI limits explained
- UK mortgage affordability calculator and borrowing guide for 2026
- How UK lenders assess self-employed mortgage affordability including CIS and contractor income
- Bank of England and PRA consultation on high loan-to-income lending and the LTI flow limit
- FCA plans for the future mortgage market including stress test flexibility and affordability reform