
If you earn a decent salary but still cannot borrow enough to buy the home you want, you are not alone, and a standard joint mortgage is not always the answer. A joint borrower sole proprietor mortgage (JBSP) lets a parent, grandparent, or close family member add their income to your application without their name ever appearing on the property deeds. The result: a bigger mortgage, no stamp duty surcharge triggered by the helper’s existing homeownership, and full legal ownership staying with you. It is one of the most practical, and most misunderstood, mortgage structures available in the UK today.
Table of Contents
- What Is a Joint Borrower Sole Proprietor Mortgage?
- Quick Takeaways
- How JBSP Mortgages Work in Practice
- Stamp Duty and JBSP: The Key Tax Advantage
- Who Qualifies for a JBSP Mortgage?
- Which Lenders Offer JBSP Mortgages in the UK?
- JBSP vs Guarantor vs Joint Mortgage: A Clear Comparison
- Risks and Disadvantages You Must Understand
- Planning Your Exit: Removing a Joint Borrower
- Who Benefits Most from a JBSP Mortgage?
- Frequently Asked Questions
- References
What Is a Joint Borrower Sole Proprietor Mortgage?
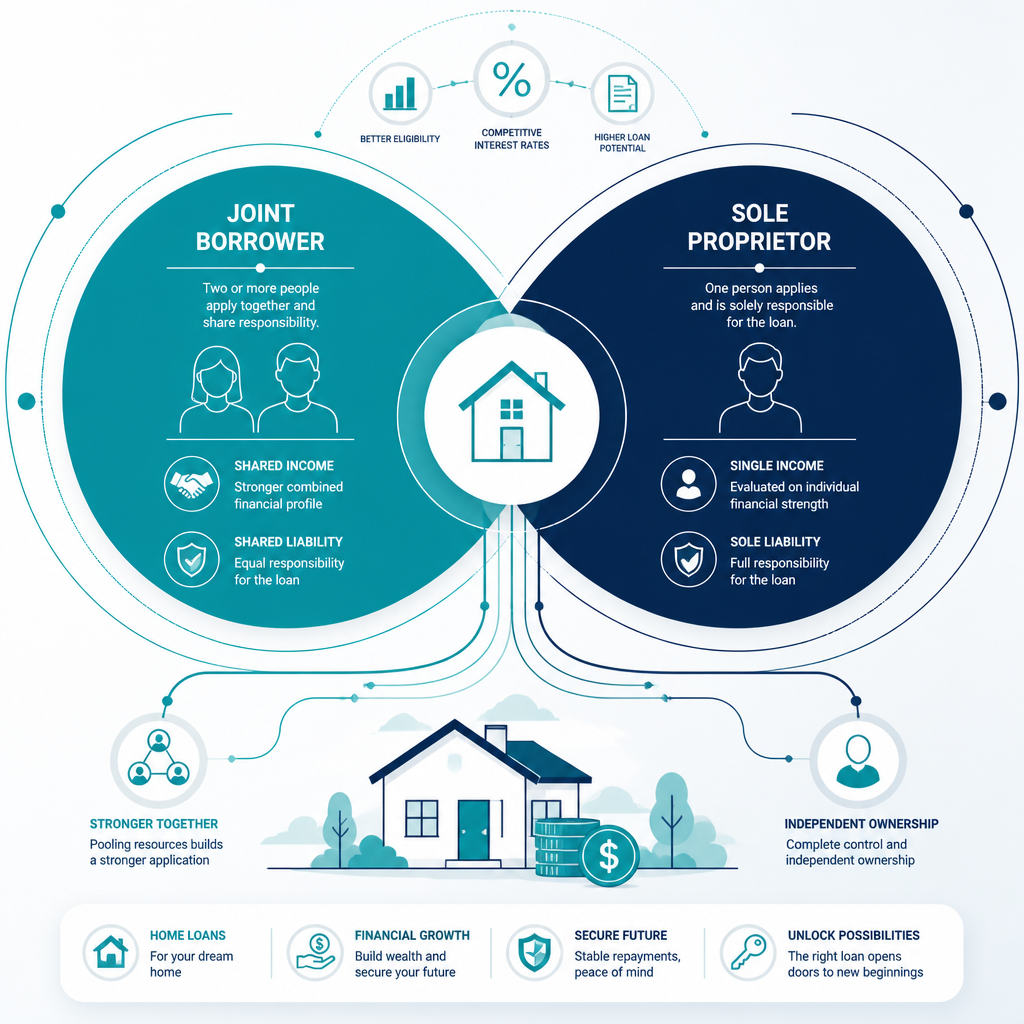
A JBSP mortgage is a mortgage product where up to four people can be named as borrowers on the loan, but only one person (or sometimes two) is named as the legal owner on the property title deeds. Every borrower is jointly and severally liable for the repayments. Only the sole proprietor owns the home, benefits from any increase in its value, and holds the legal rights over the property.
The borrowers who are not on the deeds are sometimes called “supporting borrowers” or “income boosters.” Their income is counted in full during the affordability assessment, which directly increases the amount you can borrow. They have no legal claim over the property. They do not appear in the Land Registry record. They cannot make decisions about selling or remortgaging.
This is not a loophole or a workaround – it is a formally structured mortgage product offered by major high street banks and building societies across the UK. The arrangement has distinct legal and tax consequences that differ significantly from a standard joint mortgage, which is why getting proper advice before applying matters enormously.
Quick Takeaways
| Key Insight | Explanation |
|---|---|
| Ownership stays with you | Only the sole proprietor(s) appear on the property title deeds, regardless of how many people are on the mortgage. |
| First-time buyer relief is protected | Because supporting borrowers are not on the deeds, the sole proprietor’s first-time buyer status is unaffected – a significant stamp duty saving. |
| No additional dwelling surcharge from helpers | A parent who already owns a home does not trigger the higher SDLT rate on the purchase, because they are not legally acquiring the property. |
| All borrowers face credit checks | Every person named on the mortgage is assessed for creditworthiness and income. A poor credit profile from any borrower can affect the application. |
| Up to four borrowers allowed | Most lenders permit up to four applicants on the mortgage, though each lender sets its own maximum and relationship rules. |
| Supporting borrowers carry real financial risk | If repayments are missed, all borrowers’ credit scores are affected – including the helper’s – even though they own nothing. |
| Removal requires a remortgage | To remove a joint borrower in the future, the sole proprietor must typically remortgage and prove their income alone supports the debt. |
How JBSP Mortgages Work in Practice
The mechanics are straightforward, but the details matter. When you apply for a JBSP mortgage, every borrower on the application submits to a full affordability and credit assessment. The lender adds the qualifying incomes together – yours and your supporting borrower’s – and uses that combined figure to calculate how much you can borrow. Standard income multiples apply to the total.
For example, if you earn £30,000 and your parent earns £40,000, a lender applying a 4.5x income multiple might offer up to £315,000 combined, compared to £135,000 on your income alone. The exact figure depends on the lender, the individual credit profiles, and the existing financial commitments of every borrower.
The supporting borrower’s existing mortgage payments and other debts are factored into the affordability calculation as outgoings. This is a detail many people miss: if your parent still has a large mortgage on their own home, that commitment will reduce the net contribution their income makes to your affordability. A good mortgage adviser will model this carefully before you decide who to include on the application.
Who can be a supporting borrower?
Lenders vary on this, but most require the supporting borrower to be a close family member. Parents and grandparents are almost universally accepted. Some lenders also permit siblings or other close relatives. A small number of lenders will consider unrelated applicants, but this is less common and worth verifying through a broker before you set your expectations.
The supporting borrower must be a UK resident in most cases, hold a clean or acceptable credit history, and have verifiable income. Self-employed income is accepted by many lenders, including Barclays, though documentation requirements apply in the same way as for any self-employed mortgage application.
Pro tip: Before choosing who to name as your supporting borrower, ask a mortgage adviser to run the full affordability numbers including the helper’s existing debts. The person with the highest gross income is not always the person who adds the most to your borrowing power.
Stamp Duty and JBSP: The Key Tax Advantage
This is where the JBSP mortgage genuinely earns its place as a specialist product. With a standard joint mortgage, stamp duty land tax (SDLT) is assessed on the status of every buyer named on the deeds. If your co-buyer already owns a property – as most parents do – the higher rate SDLT surcharge applies to the entire purchase price, unless they are replacing their own main residence.
With a JBSP mortgage, the supporting borrower is not on the deeds. They are not acquiring any interest in the property. This means their homeownership history is irrelevant for SDLT purposes. If you are a first-time buyer and you are the sole proprietor, you benefit from first-time buyer SDLT relief as though you were buying entirely alone.
The stamp duty advantage of a JBSP mortgage over a joint mortgage can run to tens of thousands of pounds in real savings – a difference that fundamentally changes whether family help makes financial sense.
In England, first-time buyers currently pay no stamp duty on the first portion of a home’s value, up to the prevailing threshold, and a reduced rate on the portion above that up to £500,000. Beyond £500,000, standard rates apply. Always check the current thresholds at gov.uk, as these change with fiscal policy. What does not change is the structural logic: the JBSP arrangement keeps the helper off the deeds and off the SDLT assessment entirely.
Pro tip: If a parent helping you already owns a buy-to-let property, a standard joint mortgage would trigger the higher SDLT surcharge on your purchase. A JBSP mortgage eliminates that problem. This single factor often makes the difference between a family-assisted purchase being viable or not.
Who Qualifies for a JBSP Mortgage?
Eligibility is assessed at the level of every individual borrower, not just the sole proprietor. Every person on the application must pass the lender’s credit checks, and the lender will consider the full picture of their financial commitments.
Eligibility requirements for the sole proprietor
The sole proprietor must meet the lender’s standard residential mortgage criteria: employment or self-employment income that can be documented, a satisfactory credit history, and the ability to demonstrate they intend to occupy the property. Some lenders require the sole proprietor to contribute a minimum income or deposit percentage independently, rather than relying entirely on the supporting borrower’s income.
Eligibility requirements for the supporting borrower
Supporting borrowers are assessed as full mortgage applicants. Their income is included, but so are their liabilities. Key criteria typically include a good credit record, verifiable income (employed or self-employed), UK residency, and an age that allows a reasonable mortgage term – most lenders set the term to end before the oldest or youngest borrower reaches a maximum age, commonly 70 or 75. If your parents are approaching retirement, this age restriction can shorten the available term and raise monthly payments significantly.
What can disqualify an application?
A poor credit history from any borrower can sink the application or push it toward specialist lenders with higher rates. High existing debt levels for the supporting borrower reduce the net benefit of adding them. Some lenders also restrict JBSP mortgages to residential purchases only, excluding buy-to-let, and most require evidence of a credible exit plan – i.e., a realistic scenario in which the sole proprietor eventually takes on the mortgage alone.
Which Lenders Offer JBSP Mortgages in the UK?
The JBSP market has grown considerably. At least 35 banks and building societies now offer some form of JBSP product in the UK. That figure includes major high street names as well as smaller, more specialist lenders – and the criteria between them vary enough that product selection genuinely matters.
Lenders confirmed as offering JBSP products include Barclays (marketed as its Mortgage Boost product), NatWest (its Family-Backed Mortgage), Halifax, Nationwide, Metro Bank, Skipton Building Society, Leeds Building Society, Principality Building Society, Bath Building Society, Tipton and Coseley Building Society, Family Building Society, and Vida Home Loans. This is not an exhaustive list, and product availability changes regularly.
Not every lender applies the same rules. Barclays accepts up to four applicants with one sole proprietor and accepts both employed and self-employed income from all borrowers. Halifax permits up to four people on the mortgage with a requirement for UK residency and assesses the helper’s existing mortgage payments as a deduction against affordability. Criteria diverge enough that working with an independent broker who has access to the full market is the most reliable way to identify which lender suits your specific situation.
Lenders that do not offer JBSP products may default to recommending a standard joint mortgage, which often produces a worse tax outcome for the buyer. If you approach a lender directly without knowing which products exist, you are unlikely to be pointed toward the most suitable structure.
JBSP vs Guarantor vs Joint Mortgage: A Clear Comparison
These three structures are frequently confused with each other, and the wrong choice can cost you thousands in avoidable stamp duty or leave your supporting family member exposed in ways they did not anticipate.
| Feature | JBSP Mortgage | Standard Joint Mortgage | Guarantor Mortgage |
|---|---|---|---|
| Who is on the mortgage? | Buyer + supporting borrower(s) | All buyers equally | Buyer only (guarantor separate) |
| Who owns the property? | Sole proprietor only | All mortgage holders jointly | Buyer only |
| Supporting party’s income used? | Yes – fully included | Yes – fully included | Sometimes – varies by lender |
| SDLT surcharge risk from helper? | No – helper not on deeds | Yes – if helper owns other property | No – guarantor not on deeds |
| First-time buyer relief preserved? | Yes – if sole proprietor qualifies | Not if co-owner is not a first-time buyer | Yes |
| Helper’s credit risk if payments missed? | Yes – all borrowers affected | Yes – all owners affected | Yes – guarantor liable |
| Helper benefits from property value increase? | No | Yes – proportionally | No |
The guarantor mortgage is often seen as the closest alternative to a JBSP, but in practice the two products work differently. With a traditional guarantor mortgage, the guarantor is liable only if the borrower defaults, which means their income is not always used to expand the borrowing limit. With a JBSP, the supporting borrower’s income is used from the outset to calculate the maximum loan – that is the primary reason buyers choose this structure.
Risks and Disadvantages You Must Understand
A JBSP mortgage is a genuinely useful tool, but it is not the right product for every situation. Understanding what can go wrong matters as much as understanding what can go right.
Joint and several liability
Every borrower is equally responsible for the full mortgage payment, regardless of their ownership status. If the sole proprietor stops paying, the lender can pursue the supporting borrower for the arrears. A missed payment damages every borrower’s credit record, not just the person who lives in the property. This is not a theoretical risk – families go through financial difficulties, relationships change, and the supporting borrower has no legal control over the property that would give them any ability to resolve the situation.
Impact on the supporting borrower’s own borrowing capacity
When a parent or relative joins a JBSP mortgage, their own affordability for any future borrowing is reduced. Lenders assessing a new application from the supporting borrower will see the JBSP mortgage as an existing liability. This matters if the supporting borrower plans to remortgage their own home, purchase an investment property, or take out any other form of credit. This is a real and frequently underestimated consequence.
Age restrictions and term length
Most lenders set the maximum mortgage term based on the age of one of the borrowers, often the eldest. If your supporting borrower is 55, the lender might allow only a 15-year term to bring the mortgage to its end point before or at retirement age. A shorter term means higher monthly payments, which can undermine the affordability benefit of adding the supporting borrower in the first place.
Limited lender pool and potentially higher rates
Although the JBSP market has grown, it remains smaller than the standard residential mortgage market. Some lenders charge a modest premium on JBSP products to reflect their assessment of complexity. Working with an independent adviser who can compare the full market is essential to avoid overpaying.
Relationship risk
The people most likely to help you with a JBSP are the people closest to you. If those relationships deteriorate, resolving the mortgage arrangement can be expensive, emotionally difficult, and legally complex. Exiting the arrangement requires the sole proprietor to remortgage in their sole name, which depends on their income at that point being sufficient.
Planning Your Exit: Removing a Joint Borrower
This is the part of JBSP planning that gets the least attention during the initial application and causes the most problems later. Every JBSP arrangement should begin with a clear understanding of how and when the supporting borrower will be removed.
Removing a joint borrower typically requires the sole proprietor to remortgage the property in their sole name. The new lender will assess affordability based on the sole proprietor’s income alone at that point. If the sole proprietor’s income has not grown sufficiently since the original purchase, or if interest rates have risen, they may not pass the solo affordability test – and the supporting borrower remains on the mortgage against their wishes.
Some supporting borrowers want to be removed because they are planning a property purchase of their own and need their income freed from the JBSP commitment. This is a practical and legitimate concern that should be discussed openly before the arrangement is set up. If a plausible exit timeline cannot be identified – for example, “I expect my income to reach £X in three years” – that is a signal to reconsider whether a JBSP is the right structure or whether additional planning is needed.
There is no automatic trigger that removes a borrower from the mortgage. Lenders do not proactively approach the sole proprietor to offer a switch to a solo mortgage. The exit must be initiated actively, and it may involve conveyancing costs, remortgage fees, and a new credit assessment. Building these costs into your financial planning from day one is not pessimistic – it is sensible.
Who Benefits Most from a JBSP Mortgage?
At Albion Forest, we advise clients on JBSP mortgages across a range of circumstances, and the product consistently works best in specific situations rather than as a general affordability fix.
First-time buyers in higher house price areas who have family willing and able to help are the most natural candidates. The combination of an expanded borrowing capacity and preserved first-time buyer SDLT relief makes a compelling case where other structures would either limit borrowing or create a tax cost.
Buyers with fluctuating income – including freelancers, CIS contractors, and self-employed professionals – sometimes struggle to demonstrate sufficient income on their own, particularly if they have only recently moved into self-employment. A JBSP that includes a parent with stable employed income can bridge that gap while the buyer’s own financial track record builds. This intersects directly with the specialist mortgage advice we provide for self-employed clients, where income verification and lender selection already require careful handling.
Couples where one partner has a significantly stronger income or cleaner credit profile than the other sometimes use a JBSP to structure the arrangement so that only the stronger borrower is on the deeds. This avoids inheritance complications, simplifies property planning, and prevents an adverse credit history from dragging down the application.
Teachers, nurses, and other key workers who benefit from sector-specific mortgage products can sometimes combine those products with JBSP arrangements, though this depends on the lender and requires advice from someone who understands both the professional mortgage niche and the JBSP structure. If you fall into one of these groups, the right broker will know which lenders accommodate both simultaneously and which do not.
If you are unsure whether a JBSP is the right structure for your circumstances, an initial conversation with one of the advisers at Albion Forest costs you nothing and covers the full picture, including whether a first-time buyer mortgage, a standard family joint mortgage, or a more specialist product would serve you better. We also work across the UK, so advice is available online, by phone, or face to face regardless of where you are buying.
Frequently Asked Questions
Does a JBSP mortgage affect the supporting borrower’s own mortgage?
Yes, it does. When the supporting borrower applies for any future credit – including remortgaging their own home – lenders will see the JBSP mortgage as a financial commitment. This reduces the supporting borrower’s assessed affordability for new borrowing, even though they own no part of the property secured by the JBSP. This consequence should be discussed and understood clearly before anyone agrees to join as a supporting borrower.
Can I use a JBSP mortgage if my parents already own their own home?
Yes, and this is one of the main reasons JBSP mortgages are used. Because the supporting borrower is not placed on the property deeds, their existing homeownership does not trigger the higher rate stamp duty surcharge that would apply on a standard joint mortgage. The sole proprietor’s first-time buyer status is also preserved, provided all people named on the deeds qualify as first-time buyers.
How many people can be named on a JBSP mortgage?
Most lenders permit up to four borrowers on the mortgage in total, though each lender sets its own limit and may have rules about the relationship between borrowers. The sole proprietor can be one or sometimes two people. The remaining borrowers are the supporting borrowers who appear on the mortgage but not on the title deeds.
Can a self-employed person use a JBSP mortgage?
Yes. Self-employed income is accepted by a number of JBSP lenders, including Barclays. Both the sole proprietor and the supporting borrower can be self-employed, though each will need to provide appropriate documentation – typically two years of accounts or tax returns. Some lenders are more flexible on this than others, which is another reason why lender selection through an experienced broker matters. For CIS contractors and freelancers specifically, income calculation methods differ between lenders and can substantially affect the borrowing figure.
What happens if repayments are missed on a JBSP mortgage?
All borrowers named on the mortgage are jointly and severally liable. This means the lender can pursue any one of them for the full outstanding amount. Missed payments are recorded on every borrower’s credit file – not just the sole proprietor’s. In a worst-case scenario of repossession, every borrower’s creditworthiness is affected, even though only the sole proprietor had legal ownership of the property. This shared risk is the most significant downside of the arrangement and should be part of any honest conversation before proceeding.
Is a JBSP mortgage the same as a guarantor mortgage?
No. They are similar in purpose but different in structure. With a guarantor mortgage, the guarantor steps in only if the borrower defaults – their income is not always used to calculate the maximum loan size. With a JBSP mortgage, the supporting borrower’s income is included in the affordability assessment from the start, which is why JBSP tends to unlock more borrowing. Both products keep the helper off the property deeds, but the financial mechanics and lender treatment differ.
Can the supporting borrower be removed from the mortgage later?
Yes, but it requires action – it does not happen automatically. The sole proprietor must remortgage in their sole name and pass a new affordability assessment based only on their own income at that point. If their income has not grown enough, or if rates have moved significantly, this may not be possible immediately. Planning a realistic timeline for this transition is important and is something a good mortgage adviser will help you model at the outset, not as an afterthought.
Have you used a joint borrower sole proprietor mortgage, or are you currently weighing it up against other options? Share your experience or questions below – we read every comment and aim to respond promptly.
References
- Suffolk Building Society: JBSP Mortgage Stamp Duty Explained
- Family Building Society: Joint Borrower Sole Proprietor Mortgage Product Page
- Trinity Financial: Which Lenders Offer JBSP Mortgages in the UK
- Unmortgageable: JBSP Mortgage Lender Criteria and Requirements
- Unbiased: What Is a Joint Borrower Sole Proprietor Mortgage?