
Most borrowers asking about an interest only mortgage UK get a vague answer: “it’s available, but harder to get than it used to be.” That is technically true but practically useless. The real picture is more specific. Interest-only mortgages remain available in 2026 across a range of lenders, but the approval gate has shifted from income and loan-to-value alone to something more exacting: the credibility, documentation, and long-term viability of your repayment plan. Get that right and you can access significantly lower monthly payments. Get it wrong and you can be declined by lenders who might otherwise approve your income and deposit without hesitation.
Table of Contents
- Quick Takeaways
- How Interest Only Mortgages Work in 2026
- Who Qualifies: Eligibility Criteria Across Lenders
- Repayment Vehicles: What Lenders Actually Accept
- Interest Only for Self-Employed and CIS Contractors
- Interest Only for Buy-to-Let Investors
- Comparing Interest Only Structures
- How to Apply for an Interest Only Mortgage in the UK
- FCA Rule Changes: What Is Shifting in 2026
- Frequently Asked Questions
- References
Quick Takeaways
| Key Insight | Explanation |
|---|---|
| Repayment vehicle is the main approval gate | Lenders assess the credibility and documentation of your repayment plan at least as seriously as your income. An undocumented or vague plan is the most common reason for a decline. |
| Minimum income requirements vary widely | Some lenders set income thresholds of £75,000 sole or £100,000 joint. Others have dropped floors entirely, assessing repayment vehicle sufficiency instead. There is no universal rule. |
| LTV caps are typically 60-85% depending on lender and vehicle | Most residential lenders cap interest-only at 75% LTV. Some go higher with high income or multiple vehicles. Sale of mortgaged property as the vehicle often carries a lower LTV ceiling. |
| Buy-to-let is the most straightforward path | Interest-only is the standard structure for buy-to-let mortgages in the UK. The repayment vehicle – eventual property sale – is widely accepted without the documentation burden of residential cases. |
| Self-employed and CIS contractors face additional income evidence requirements | Your income must be verified through accounts, SA302 forms, or CIS payslips depending on lender appetite. The product itself is the same – income assessment is what differs. |
| The FCA’s CP26/18 proposals may relax some rules | A 2026 FCA consultation proposes removing the requirement for a documented repayment strategy where the interest-only element is below 25% of the property valuation. Final rules are expected in H2 2026. |
| Part-and-part mortgages offer a practical middle ground | A part-and-part structure combines a capital repayment portion with an interest-only portion, reducing the repayment vehicle burden while still lowering monthly costs versus a full repayment mortgage. |
How Interest Only Mortgages Work in 2026
An interest only mortgage requires you to pay only the monthly interest charge. The capital balance, the actual amount borrowed, stays exactly as it was on day one. At the end of the mortgage term, you repay the full original loan in a single payment. That payment must come from a separately maintained repayment vehicle: an investment portfolio, a pension lump sum, the sale of a property, or a combination of these.
The practical effect on monthly payments is significant. On a £300,000 mortgage at 4.5% interest, a capital repayment mortgage over 25 years costs roughly £1,660 per month. The same loan on interest-only terms costs around £1,125 per month. That difference in cash flow is why interest-only remains attractive to higher earners, buy-to-let investors, and professionals managing liquidity across multiple assets.
Interest-only lending in 2026 is no longer assessed purely on income multiples and loan-to-value. It is evaluated through the lens of long-term repayment viability.
What has changed significantly since the pre-2008 era is oversight. Under the FCA’s responsible lending rules in MCOB 11.6, lenders must verify a credible repayment strategy before granting an interest-only loan, and must check in with borrowers periodically throughout the term to confirm the plan remains on track. This is not advisory. It is a contractual obligation on both sides.
Who Qualifies: Eligibility Criteria Across Lenders
There is no single answer to who qualifies for an interest only mortgage in the UK because eligibility criteria vary substantially between lenders. That variability is exactly why using a broker who knows the market matters. What gets you declined at one lender may be straightforwardly approved at another.
Income Requirements
Some mainstream lenders still apply income floors. As a reference point, one major high street lender requires a minimum sole income of £75,000 or a joint income of £100,000, with the joint application qualifying provided at least one applicant earns above the sole threshold. Other lenders have removed minimum income thresholds altogether, instead assessing whether income is sufficient to support an equivalent capital repayment mortgage under stress-tested conditions.
The practical effect of this variation is that a borrower earning £55,000 may be declined at one lender and approved at another, depending entirely on which lender they approach and which repayment vehicle they bring. Getting the right match matters far more than meeting a headline number.
Loan-to-Value Limits
Most residential lenders cap interest only mortgage eligibility UK at 75% LTV, meaning you need at least a 25% deposit or 25% equity. Some lenders offer up to 85% LTV for borrowers with high incomes and multiple documented repayment vehicles. Where the sale of the mortgaged property itself is the repayment vehicle, the LTV ceiling tends to drop further, often to 60%, because the equity buffer needs to remain large enough to make downsizing realistic at term end.
Leeds Building Society, for example, caps interest-only at 60% LTV for standalone interest-only, rising to 75% LTV for part-and-part structures where the interest-only element does not exceed 60% of the total loan. Coventry for Intermediaries requires a minimum of £200,000 equity remaining in the property after the mortgage is taken. These are not unusual positions. They reflect how seriously lenders take exit realism when the repayment vehicle is property itself.
Age Constraints
Most lenders set a maximum age at the end of the mortgage term, commonly the borrower’s 70th birthday or their anticipated retirement age, whichever is lower. On joint applications, the age of the oldest applicant typically governs the calculation. If you are 52 and applying for a 25-year interest-only term, the lender will assess whether your repayment vehicle will be accessible and sufficient by age 77 – and some will decline on age grounds alone if the term pushes past their policy limit.
Pro tip: If age is a constraint on a standard residential interest-only product, a Retirement Interest-Only mortgage (RIO) may be worth exploring. RIO mortgages are specifically designed for older borrowers and use the sale of the property on death or entry into long-term care as the primary repayment vehicle, with no fixed end date to the term.
Repayment Vehicles: What Lenders Actually Accept
The repayment vehicle interest only requirement is the part of the process where applications succeed or fail in practice. A repayment vehicle is a documented, plausible plan for repaying the capital balance at term end. Lenders are not looking for hope. They are looking for an evidenced, measurable strategy that holds up under conservative assumptions.
Accepted Repayment Vehicles in 2026
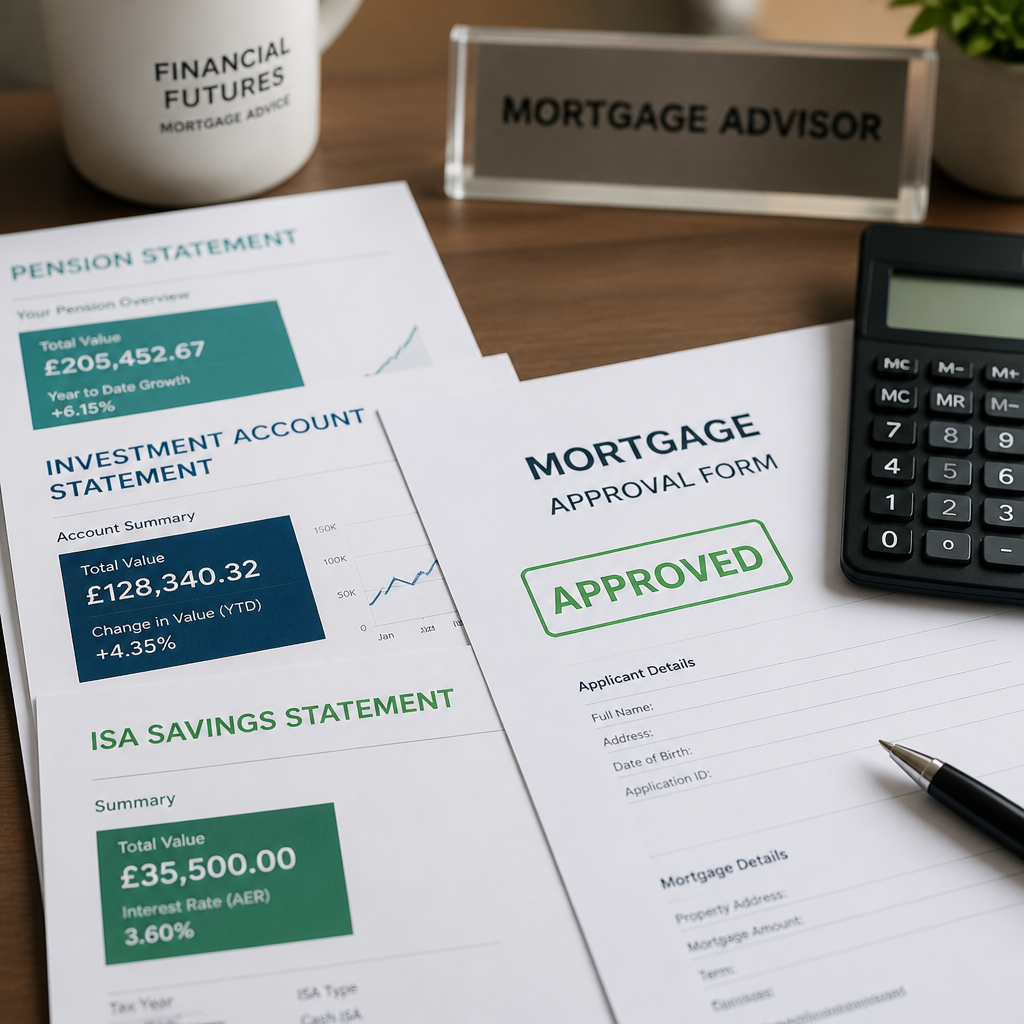
The main vehicles accepted by most lenders include: the sale of the mortgaged property (subject to minimum equity thresholds), stocks and shares ISAs and investment portfolios, pension tax-free lump sums, endowment policies, savings plans, the sale of a second property, and combinations of the above. Lenders typically require evidence no older than 12 months: current investment statements, pension projection letters from the scheme provider, professional property valuations, or proof of ownership of additional assets.
Where investments are proposed, many lenders apply a conservative haircut to current portfolio values to account for market volatility. A £500,000 investment portfolio may be assessed at a discounted value for underwriting purposes. Where pensions are proposed, the key figure is the projected tax-free lump sum entitlement at the mortgage end date, not the total fund value. These distinctions matter when you are calculating whether your vehicle is sufficient on paper.
Pro tip: Never present multiple vehicles as a loosely combined plan without independent documentation for each. Lenders treat a well-documented single vehicle more favourably than a poorly evidenced collection of assets that individually fall short. Get pension projections formally requested from your provider, and obtain current valuations of any investment accounts before application.
Sale of Mortgaged Property as a Vehicle
Using the sale of the property you are buying as the repayment vehicle is accepted by a number of lenders, but the conditions are specific. The equity cushion must make downsizing genuinely realistic at the end of the term. Lenders want confidence that after selling and buying something cheaper, you will clear the mortgage balance and still be able to fund a replacement home. Some lenders require a minimum equity of £200,000 to £300,000 (with higher thresholds in London and the South East) for this route to be available at all.
Interest Only for Self-Employed and CIS Contractors
If you are self-employed or working under the Construction Industry Scheme, an interest-only mortgage is available through the same product range as any other borrower. The product is not different. What differs is how your income is assessed, and that assessment affects which lenders you can access and what loan sizes are available to you.
How Lenders Assess Self-Employed Income
Most lenders classify you as self-employed if you own 20-25% or more of the business that generates your primary income. Sole traders are typically assessed on net profit. Limited company directors are generally assessed on salary plus dividends. Lenders want to see two to three years of accounts, SA302 tax calculations, and corresponding tax year overviews from HMRC. Some specialist lenders will consider one year of trading history in the right circumstances.
For CIS contractors, the picture is more nuanced. A subset of lenders will assess CIS income based on gross CIS payslips rather than treating you as standard self-employed, which means accounts and tax returns are not required. This matters significantly because CIS contractors often retain lower net income figures in their accounts than their actual gross earnings reflect. Using a lender that accepts CIS payslip income directly can substantially increase the loan available to you.
Combining Self-Employed Status with Interest-Only
The combination of self-employed income and an interest-only application is not a red flag by itself. What lenders are looking for is consistency between income verification and repayment vehicle viability. If your repayment vehicle is an investment portfolio or pension, the same documentation standards apply regardless of employment status. Where self-employed applicants can run into difficulty is when income variability in recent years creates uncertainty about the long-term sustainability of interest payments – especially under lender stress tests. Using a specialist mortgage adviser for self-employed applicants is not optional here. It is the difference between being presented to the right lender or spending months in unsuccessful applications.
Interest Only for Buy-to-Let Investors
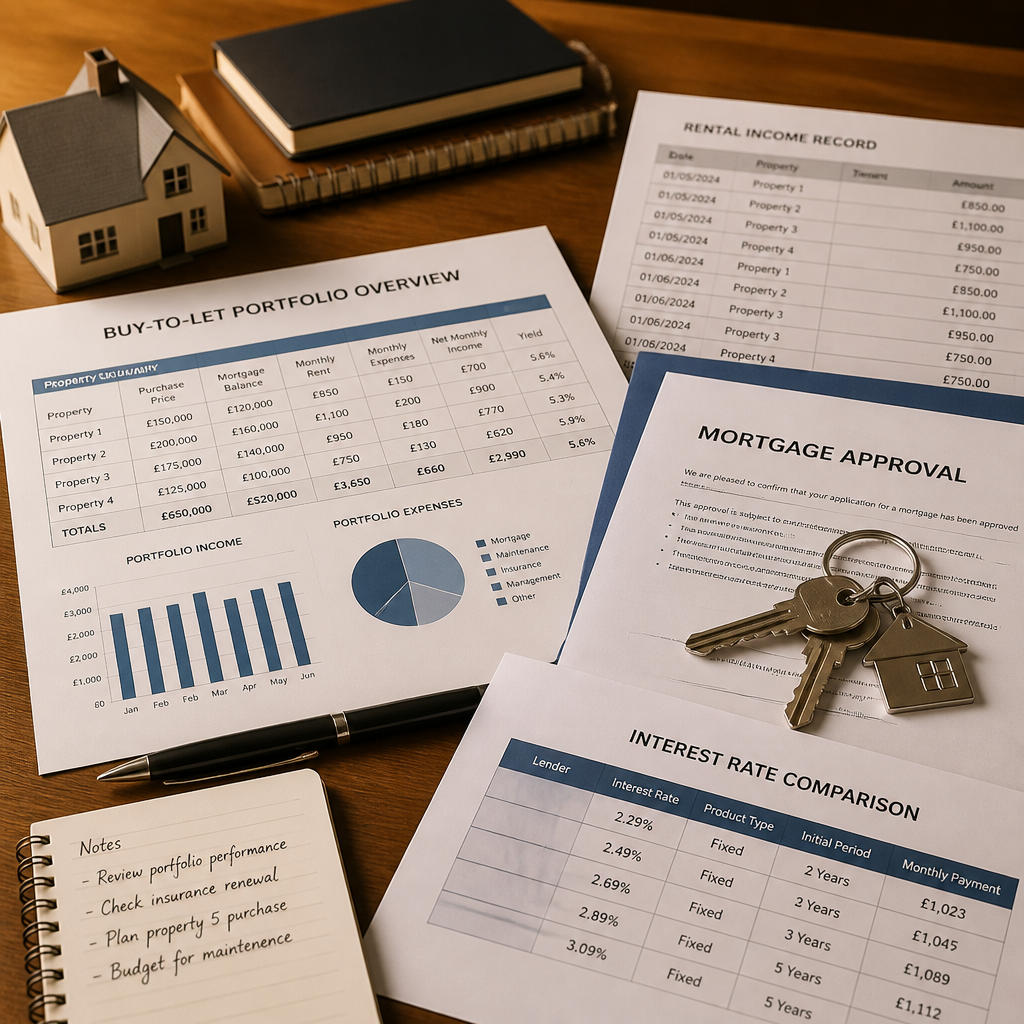
For buy-to-let mortgage borrowers, interest-only is not a specialist product. It is the standard structure used across the overwhelming majority of buy-to-let lending in the UK. The repayment vehicle is the eventual sale of the investment property, which lenders accept without the same documentation burden as residential repayment plans.
Buy-to-let interest-only lending is assessed primarily on rental income coverage: lenders apply an interest coverage ratio (ICR) test, typically requiring rental income to cover between 125% and 145% of the monthly interest payment, often calculated at a stressed rate above the actual mortgage rate. If the rent does not pass the ICR test at the lender’s stress rate, the available loan is reduced until it does.
For portfolio landlords owning four or more mortgaged properties, some lenders apply additional stress testing across the entire portfolio rather than just the single property being purchased. This is not a barrier if you are well organised. It is simply another documentation requirement that needs to be prepared correctly from the outset.
Comparing Interest Only Structures
Not all interest-only borrowing looks the same. Depending on your circumstances and repayment strategy, three distinct structures are available to most UK borrowers in 2026. Understanding the practical differences helps you choose the right approach and present it clearly to a lender.
| Structure | How It Works | Best Suited For |
|---|---|---|
| Full Interest-Only | Monthly payments cover interest only for the full term. Capital remains constant and is repaid in full at the end from an approved repayment vehicle. Lowest monthly cost of the three structures. | Higher earners with a well-documented repayment vehicle (pension, large investment portfolio, property sale). Buy-to-let investors. Borrowers managing short-to-medium-term cash flow. |
| Part-and-Part Mortgage | A portion of the loan is on a capital repayment basis; the remainder is interest-only. The capital element reduces over time, lowering the amount that must be repaid via the repayment vehicle at term end. | Borrowers whose repayment vehicle is not large enough to service the full loan on interest-only terms, but who still want lower payments than a full repayment mortgage provides. Good for self-employed borrowers with growing portfolios. |
| Retirement Interest-Only (RIO) | No fixed end date. Monthly payments cover interest indefinitely. Capital is repaid when the property is sold, typically on death or entry into long-term care. Assessed on current income only, not projected future income. | Borrowers aged 55 and over who do not have a traditional repayment vehicle but have substantial equity and a stable pension or retirement income. Also useful for equity release alternatives. |
How to Apply for an Interest Only Mortgage in the UK
Applying for an interest only mortgage UK follows the same general process as any mortgage application, but with an extra layer of preparation around repayment vehicle documentation. Going into this unprepared is where most interest-only applications encounter problems.
Step 1: Clarify Your Repayment Vehicle Before You Apply
This step comes before you speak to any lender. Identify which vehicle or combination of vehicles you intend to use, and gather current evidence for each. For pensions, request a formal projection from your pension provider showing the anticipated tax-free lump sum at the mortgage end date. For investments, obtain a current statement and confirm the lender’s expected evidence format. For property, have a current valuation available and know the equity figure precisely.
A common mistake is treating the repayment vehicle as an afterthought, something to document after the lender expresses interest. Lenders assess it at the same time as income and LTV. Arriving without it documented is equivalent to arriving without a payslip.
Step 2: Work Out Which Lenders Accept Your Profile
Given the wide variation in income floors, LTV limits, acceptable vehicles, and age constraints between interest only mortgage lenders UK 2026, the most important step before applying is identifying which lenders will actually consider your combination of circumstances. This is where working with a whole-of-market adviser adds clear value. The adviser checks eligibility across the lender panel before you make a formal application, protecting your credit record from unnecessary hard searches.
Step 3: Prepare Income Documentation
For employed borrowers, standard payslips and P60s apply. For self-employed borrowers and CIS contractors, the documentation required depends on which lender you are applying to. Some will want two years of accounts and SA302s. Others will work from CIS payslips directly. Knowing this before submission avoids delays and prevents you from being assessed under the wrong income framework for your situation.
Step 4: Submit a Complete, Consistent Application File
Interest-only applications receive additional scrutiny from underwriters. Every element, income, LTV, repayment vehicle, age at term end, and evidence currency, needs to be internally consistent and clearly presented. Where repayment vehicles are combined, each must be independently evidenced and individually sufficient to contribute its share of the repayment plan. A well-prepared application submitted to the right lender moves quickly. A poorly prepared one stalls regardless of how strong the underlying finances are.
Pro tip: If you have been declined for an interest-only mortgage, get a written explanation of the specific grounds for decline before applying elsewhere. Many applicants reapply with the same presentation to a different lender and get declined again for the same avoidable reason. Understanding the precise objection lets you address it directly in the next application.
FCA Rule Changes: What Is Shifting in 2026
The regulatory landscape for interest-only lending is not static. In June 2026, the FCA published consultation paper CP26/18, which proposes a meaningful relaxation of certain interest-only rules that have been in place since 2014. These proposals are not yet final rules, but they indicate the direction the market is moving and may change the eligibility picture for some borrowers by the end of the year.
The most significant proposal in CP26/18 is the removal of the requirement to demonstrate a credible repayment strategy where the interest-only element represents less than 25% of the property’s valuation. For higher balances, tiered evidential requirements would apply, with the existing sale-of-property expectations retained where the interest-only element exceeds 50% of the valuation. The FCA has indicated it intends to publish a Policy Statement in H2 2026.
Separately, under the Government’s Mortgage Charter, lenders are permitted to allow borrowers who are up to date with payments to switch temporarily to interest-only for up to six months without a full affordability reassessment. The FCA introduced supporting rules to enable this. Between July 2023 and June 2026, the monthly payments on around 354,000 mortgages were reduced through this temporary interest-only or term extension route. That figure gives a sense of how many UK borrowers are actively using interest-only provisions, even temporarily, as a cash flow management tool.
For first-time buyers and underserved borrower groups, CP26/18 also proposes allowing lenders to use a structured conversation approach where formal repayment vehicle evidence is not reasonably available, provided the lender documents the dialogue and the borrower’s understanding of their plan. This is a notable shift from the current evidence-first framework.
Frequently Asked Questions
Can first-time buyers get an interest only mortgage in the UK?
Yes, some lenders do offer interest-only mortgages to first-time buyers, though the criteria are stricter than for existing homeowners. You will need to meet the lender’s income threshold and provide a credible, documented repayment vehicle. In practice, most first-time buyer interest-only cases involve higher earners who have a specific reason for wanting lower monthly payments in the early years, such as a pension plan or investment portfolio already in place. It is not common, but it is not impossible either.
What happens if my repayment vehicle falls short at the end of the term?
This is a serious risk that needs to be understood before taking out an interest-only mortgage. If your repayment vehicle does not generate enough to repay the capital balance, you will still owe the full outstanding loan on the final day of the term. Options at that point include extending the mortgage term (subject to the lender’s age and income criteria), selling the property, switching to a repayment mortgage for a final period, or refinancing. Some lenders can extend interest-only mortgages by up to 20 years, subject to a full reassessment. None of these outcomes are guaranteed, which is why maintaining and reviewing your repayment vehicle throughout the term is essential, not optional.
Can I switch my existing repayment mortgage to interest only?
You can apply to switch to interest-only if you are eligible under your current lender’s criteria. The lender will reassess your income, credit history, and repayment vehicle before agreeing. If you are not eligible with your current lender, you may be able to remortgage to a different lender that will accept an interest-only structure. Under the Mortgage Charter, borrowers up to date with payments can also switch temporarily to interest-only for up to six months without a full affordability reassessment, as a short-term measure.
Is an interest only mortgage a good idea for self-employed borrowers?
For many self-employed borrowers, the lower monthly payment of interest-only is attractive precisely because income can be variable. However, the interest-only product still requires a credible repayment vehicle that is documented and independently evidenced. Self-employed borrowers whose business is growing and who are building investment or pension assets alongside their mortgage are often well-positioned for interest-only. The key is matching the application to a lender who understands self-employed income assessment, rather than defaulting to a high street lender that assesses on a narrow employed-income model.
How does interest-only work for buy-to-let mortgages specifically?
Buy-to-let interest-only mortgages operate on the same capital-deferred principle, but the affordability assessment is driven primarily by rental income rather than personal income. The lender applies an interest coverage ratio test to ensure the rent exceeds a minimum multiple of the interest payment, typically at a stressed rate. The repayment vehicle is generally accepted as the eventual sale of the investment property, without the same documentation burden required in residential interest-only cases. This is why interest-only is the default structure for the majority of UK buy-to-let borrowing.
Will the FCA’s CP26/18 proposals make it easier to get an interest only mortgage?
If finalised as proposed, CP26/18 would remove the requirement for a documented repayment strategy where the interest-only element is below 25% of the property valuation, which would open interest-only access to a broader range of borrowers who currently struggle to evidence a formal vehicle. The FCA aims to publish final rules in H2 2026. Until those rules are confirmed and lenders have updated their criteria, current requirements remain in place. Watch for lender policy updates later in the year once the Policy Statement is published.
Have you been through an interest-only mortgage application in the UK recently, or are you currently weighing up whether it suits your situation? We would be glad to hear what questions you still have.
References
- Interest-only mortgages in 2026: repayment vehicles, risk assessment and lender criteria
- Interest-only mortgage affordability: LTV, equity and repayment vehicle guidance
- FCA mortgage rule changes 2026: what CP26/18 proposes for interest-only lending
- Interest-only mortgages UK 2026: legal rules, repayment duties and FCA obligations
- FCA consultation on targeted mortgage rule reforms for first-time buyers and underserved borrowers