
Most people stick with a mortgage broker far longer than they should. It is uncomfortable to walk away, especially mid-application, and there is always a nagging question: what if the next one is no better? But the cost of staying with the wrong broker is not just frustration. It can be the difference between an approval and a rejection, between a competitive rate and one that quietly costs you thousands over the term. If you are weighing whether to switch mortgage broker UK, this guide gives you the specific warning signs to watch for and a clear picture of what a good broker actually looks like.
Table of Contents
- Quick Takeaways
- Sign 1: Your Broker Has a Restricted Lender Panel
- Sign 2: Communication Has Broken Down
- Sign 3: Your Specialist Circumstances Are Being Ignored
- Sign 4: Fees Were Not Explained Clearly Upfront
- Sign 5: You Are Being Pushed Toward a Decision
- What to Look for Instead: The Hallmarks of a Better Broker
- Broker Type Comparison: Tied, Panel, and Independent Whole-of-Market
- Frequently Asked Questions
- References
Quick Takeaways
| Key Insight | Explanation |
|---|---|
| A restricted panel is not the same as whole-of-market access | A broker can legally call themselves “whole of market” while only working with a limited panel of lenders. Always ask for the lender list in writing. |
| Poor communication is a dealbreaker, not a minor inconvenience | Slow responses during underwriting can cause mortgage offers to lapse and property purchases to fall through. |
| Self-employed and CIS borrowers need a specialist, not a generalist | If your broker cannot explain how CIS gross income or limited company drawings are assessed, you are with the wrong person. |
| Fee ambiguity is a red flag | Reputable brokers disclose all fees before any work begins. Surprises later are not normal and not acceptable. |
| Pressure to decide quickly almost never serves you | Legitimate mortgage advisers give you time. Urgency tactics are designed to prevent you from comparing alternatives. |
| The FCA register is your first check | Every UK mortgage broker must be authorised by the Financial Conduct Authority. Checking takes two minutes and confirms you are dealing with a regulated adviser. |
| Switching brokers mid-process is possible and often worth it | You are not contractually locked in once an application has started, unless you have signed a specific fee agreement. A good broker can pick up your case and move fast. |
Sign 1: Your Broker Has a Restricted Lender Panel
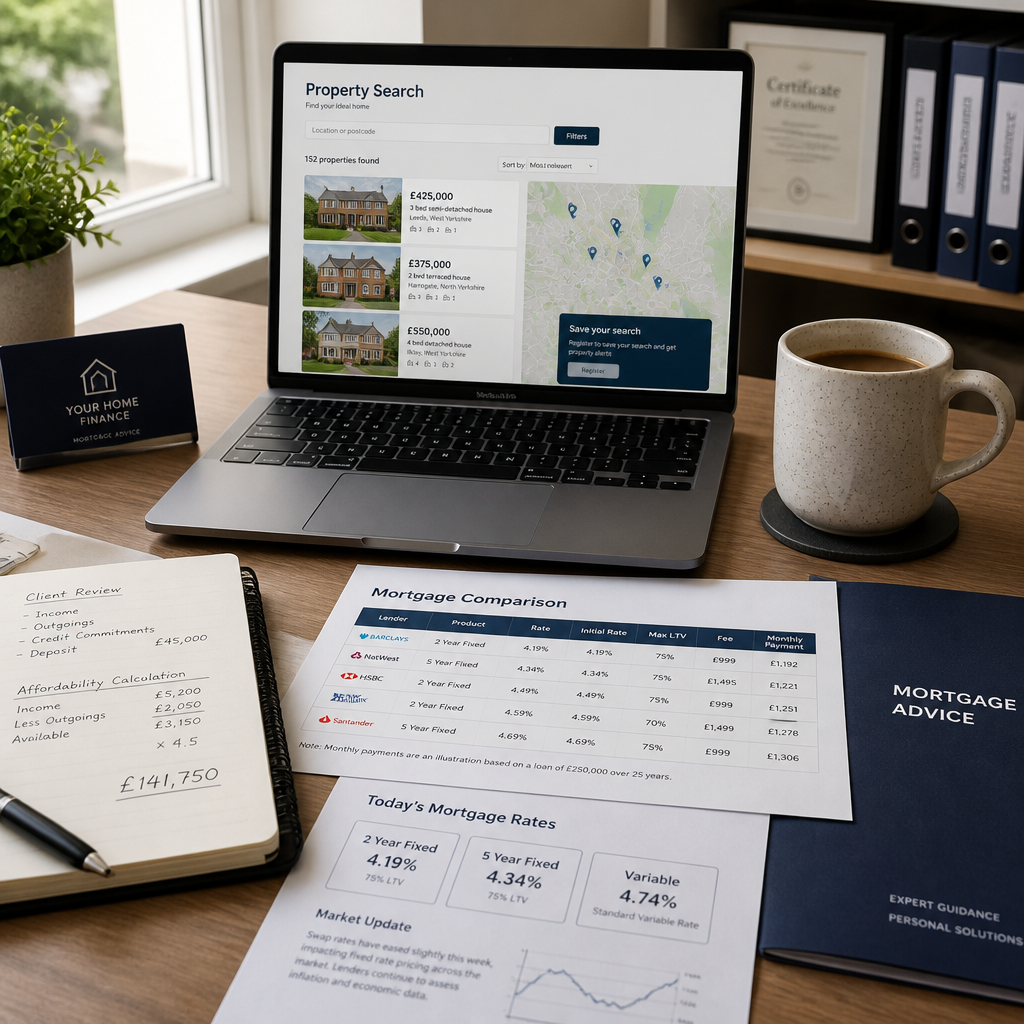
This is the most common problem and the least visible one. A broker tells you they are “whole of market” and you assume they can access every mortgage available in the UK. In practice, that phrase has a specific regulatory meaning that does not quite match what you might expect. According to the UK mortgage market, a broker can be described as whole-of-market while only working with a panel of lenders, provided that panel covers each sector of the market broadly.
For most borrowers with standard employed income and clean credit, a well-chosen panel is fine. For anyone with a more complex picture, it is a serious limitation. If your broker cannot point to specialist lenders, niche products, or non-high-street options when you ask, that panel is probably too narrow for your needs.
How to find out whether your broker’s panel is wide enough
Ask directly: “Can you give me a list of the lenders you have access to?” A good broker will not hesitate. If the answer is evasive, or if the list that comes back is dominated by the major high street names only, you are likely missing out on products that could suit your situation better.
This matters most if you are self-employed, a CIS contractor, a buy-to-let investor, or a borrower with any kind of complexity in your income or credit history. Specialist lenders assess these applications differently, and a broker without access to them simply cannot represent your full range of options.
Pro tip: Ask your broker: “Is there any lender you cannot access that I should know about?” If they cannot answer that question confidently, take it as a sign to look elsewhere for whole-of-market mortgage advice in the UK.
Sign 2: Communication Has Broken Down
A broker who goes quiet is not just frustrating. They are a liability. Mortgage applications move on timetables, and lenders, solicitors, and estate agents all need coordinated responses. When your broker is unreachable, things slip. Offers lapse. Chains collapse. Completions get delayed.
The warning signs are specific: unreturned calls or emails within two business days, vague updates that do not tell you where the application actually stands, and the sense that you are chasing more than you are being updated. One or two slow responses during a genuinely busy period can happen to anyone. A consistent pattern of poor communication is a different matter entirely.
What good communication actually looks like
A competent mortgage adviser sets clear expectations at the start: how they will contact you, how often, and what happens when something changes. They give you a named contact, not a generic inbox. They call you proactively when there is news, even when that news is “nothing has changed yet, and here is why.”
If you are currently filing your third chasing email of the week to a broker who has not acknowledged your last two, that is not a you problem. That is a them problem. Switching at that point is not disruptive; it is necessary.
A broker who is difficult to reach during the application process will be impossible to reach when something goes wrong. That is the moment you most need them.
Sign 3: Your Specialist Circumstances Are Being Ignored
Generalist mortgage advice works for a straightforward case: employed, clean credit, buying a standard residential property. The moment your situation deviates from that template, the quality of specialist knowledge matters enormously. And many borrowers only discover their broker lacks that knowledge well into the process, after time has been wasted.
The clearest sign that your specialist needs are not being served is when your broker treats your situation as if it were standard. A self-employed borrower being told to wait until they have two years of accounts when there are lenders who will consider one. A CIS contractor being assessed as self-employed rather than having their gross CIS earnings considered. A teacher or key worker being shown only mainstream products when profession-specific options exist.
The CIS contractor example
CIS contractors are a specific case where the wrong broker causes measurable financial harm. Many lenders assess CIS subcontractors on their net self-employed income after deductions, which produces a borrowing figure far below what their actual gross earnings would support. A broker who understands CIS mortgages knows which lenders will use gross CIS earnings instead, dramatically increasing the loan available.
If your broker has never raised this distinction with you, and you work under the Construction Industry Scheme, they are almost certainly leaving money on the table for you. That is a clear trigger to find a better mortgage broker in the UK.
Pro tip: When you first speak to a new broker, describe your income situation in detail and ask: “Which lenders specifically do you work with who have experience with cases like mine?” Vague reassurance is not an answer. Specific lender names and criteria are.
Sign 4: Fees Were Not Explained Clearly Upfront
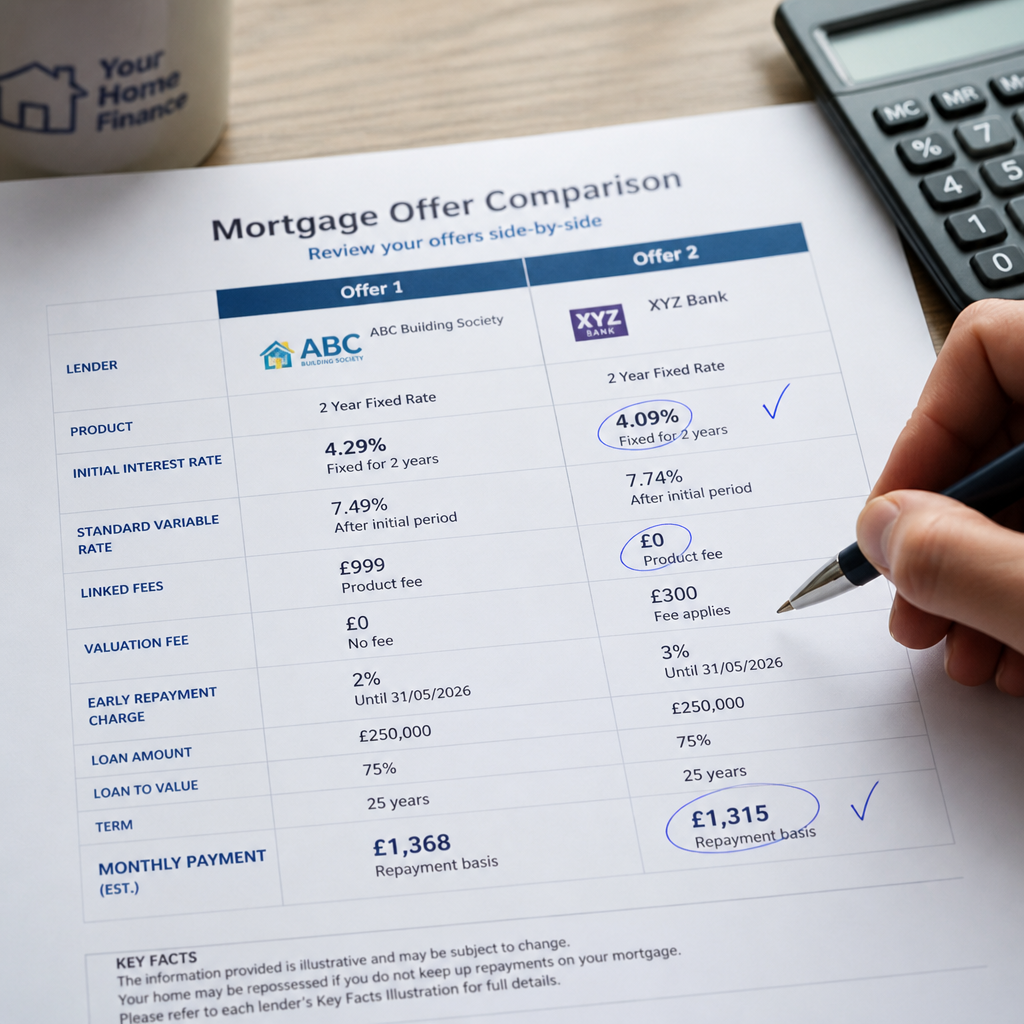
Mortgage broker fees in the UK vary widely. Some brokers charge a flat fee, some charge a percentage of the loan amount, some are fee-free and earn only from lender commission, and some combine both. None of these models is inherently wrong. What is wrong is when the fee structure is not explained clearly before you commit to working with someone.
A reputable broker will tell you exactly what you will pay, under what circumstances, and what happens to that fee if the application does not proceed. They will put it in writing. The moment you find yourself surprised by a charge you did not know about, or being asked to pay more than you were originally told, something has gone wrong.
The commission question
All FCA-regulated brokers are required to disclose the commission they receive from lenders. This is not optional and it is not something a good broker should be cagey about. If yours cannot tell you clearly what commission they will earn on the product they are recommending, that is a concern worth taking seriously.
Fee transparency connects directly to whether the advice you are receiving is genuinely in your interest. A broker who earns significantly more commission from one lender has a financial incentive to favour that lender, even if another product suits you better. You cannot evaluate that risk if the fee information is buried or withheld.
Sign 5: You Are Being Pushed Toward a Decision
Legitimate mortgage advisers do not pressure clients. They inform them. If your broker is using urgency language to push you toward a specific product, a specific lender, or a faster decision than you are comfortable making, that is a red flag regardless of whether their preferred choice is actually good value.
Phrases to watch for: “This rate is only available until Friday”, “I cannot guarantee this deal will still be there if you wait”, “You really need to commit now or you will miss the window.” Some of these statements may occasionally be true. Rates do change and products do get withdrawn. But a good broker gives you honest context, not manufactured urgency. There is a difference between “this fixed rate is expected to be pulled in the next few days and here is the evidence for that” and a vague sense that you should hurry up.
If you feel consistently rushed, always trust that instinct. You are making a financial commitment that will likely span years. The right decision, taken with a day or two more thought, is always better than the wrong decision taken immediately.
What to Look for Instead: The Hallmarks of a Better Broker
Switching broker is only useful if you know what you are switching to. The markers of a genuinely strong mortgage adviser in the UK are not complicated, but they are specific enough that most people do not ask about them directly.
FCA authorisation, verified independently
Every mortgage broker operating in the UK must be authorised by the Financial Conduct Authority. This is non-negotiable. You can check any firm’s status directly on the FCA register in under two minutes, using the firm name or their reference number. Do this before you share any personal or financial information with a new adviser.
Genuine breadth of lender access
As noted above, a broker’s lender panel matters. For borrowers with self-employed income, complex credit histories, non-standard property types, or professional circumstances that benefit from specialist products, a wide panel is not a nice-to-have. It is the difference between finding the right product and settling for whatever is available on a narrow list. The best brokers can articulate specifically which lenders they work with in your category, and why.
A track record with your type of application
Referrals from friends or colleagues who share your circumstances are the most reliable signal. If someone in a similar income situation to yours got a mortgage with a broker who understood their case from the first conversation, that broker is far more likely to serve you well than one you found at random. Reviews and ratings matter too, but look for patterns in what reviewers describe, not just star counts.
Clear, proactive communication from day one
A strong broker tells you at the outset: how they work, what the process looks like for your specific case, what information they will need and when, and how they will keep you updated. If you reach the end of a first call with a new broker and you still do not know what happens next, that is an early warning sign.
At Albion Forest Mortgages, the approach is to give every client a clear picture of their options before any recommendation is made, whether the conversation happens online, by phone, or face to face. That structure exists precisely because most mortgage problems start with a gap in information, not a gap in product availability.
Broker Type Comparison: Tied, Panel, and Independent Whole-of-Market
Understanding the differences between broker types is one of the most practical things you can do before switching. The terminology can be misleading, so the table below sets it out plainly.
| Broker Type | Lender Access | Best Suited For |
|---|---|---|
| Tied (single lender) | One lender’s products only. Often working in-branch at a bank or building society. | Borrowers who already bank with that lender and want a simple, single-stop service with no frills. |
| Panel broker (multi-lender) | A curated list of lenders, which can range from a handful to several dozen. May describe themselves as “whole of market” even if the panel is limited. | Standard residential buyers with employed income and clean credit, where a reasonable selection of mainstream products is sufficient. |
| Independent whole-of-market broker | Access to the broadest possible range of lenders, including specialist and non-high-street options. Not constrained by panel agreements. | Self-employed borrowers, CIS contractors, first-time buyers with unusual circumstances, buy-to-let investors, and anyone whose case does not fit a standard template. |
The practical implication is that if you are working with a panel broker and your case is even slightly non-standard, the best deal for you may simply not be on their list. That is not a failing on the broker’s part as a person; it is a structural limitation of the model. Knowing this upfront means you can ask the right questions rather than discovering the problem after a rejection or a substandard offer.
Frequently Asked Questions
Can I switch mortgage broker after an application has already been submitted?
Yes. You are not locked in to a broker once an application is submitted, unless you have signed a fee agreement that specifies otherwise. Switching mid-process does require your new broker to understand the existing application quickly, so choose someone experienced who can take over a case efficiently. In practice, the inconvenience of switching is almost always less damaging than continuing with a broker who is not serving you properly.
Will switching mortgage broker delay my application?
It can cause a short delay, but not necessarily a significant one. A competent replacement broker will request your documents, review the existing situation, and advise you on whether to continue with the same lender or reapply elsewhere. If the original application was with the right lender for your situation, the new broker can often continue it. If it was not, finding that out early is better than finding it out at the point of a formal decline.
How do I find a better mortgage broker in the UK?
Start with referrals from people in a similar situation to yours. A friend who is also self-employed and had a good experience with a broker is a better lead than a generic search result. Then verify the broker’s FCA authorisation, ask directly about their lender panel, and ask specifically whether they have experience with your type of application. A 5-star rating matters, but patterns in what clients describe in reviews tell you far more than the number itself.
What does “whole of market mortgage advice UK” actually mean?
The phrase means the broker is not tied to a single lender or working from a very narrow panel. However, it does not automatically mean access to every mortgage in the UK. A broker can be described as whole-of-market provided their panel covers the main sectors of the market, even if individual specialist lenders are excluded. The best way to assess genuine breadth is to ask for the lender list and to ask which types of specialist lending they can access.
Is it worth switching broker if I am a CIS contractor or self-employed?
Almost certainly yes, if your current broker does not have specific, demonstrable experience with your income type. CIS contractors in particular can be severely under-served by generalist brokers who assess their income on a standard self-employed basis rather than using gross CIS earnings. The difference in the borrowing figure available can be substantial. A broker who understands specialist income structures will ask the right questions and know which lenders to approach first.
Can switching mortgage brokers affect my credit score?
Switching broker does not itself affect your credit score. What can affect your score is multiple hard credit searches in a short period. A good broker will discuss this with you before running any searches, and will typically do a soft search first to assess your position before proceeding to a full application. If your previous broker ran a hard search and an application was submitted, discuss the timing carefully with your new broker before they initiate additional searches.
What questions should I ask a new mortgage broker before committing?
Ask: Are you FCA-authorised, and can you give me your reference number? What lenders are on your panel, and do you have access to specialist lenders in my category? What are your fees, in full, and what happens to them if the application does not succeed? Have you handled cases like mine before, and can you describe how you approached them? How will you communicate with me during the process, and what is your typical response time? A broker who answers all of these confidently and specifically is worth trusting. One who is vague on any of them is not.
We would love to hear your experience: have you switched mortgage broker mid-process, and what made the biggest difference when you did?
References
- What whole-of-market mortgage access means in the UK and how it is regulated by the FCA
- Why the difference between tied and whole-of-market brokers matters for UK borrowers in 2025
- How to assess a broker’s lender panel and what whole-of-market really covers
- How to find a mortgage broker you can trust in the UK
- Key indicators of a good mortgage broker and what to watch out for